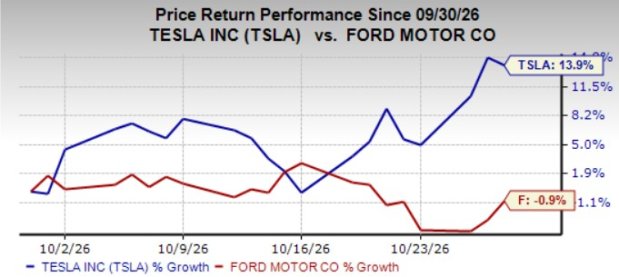
Tesla TSLA and Ford F both topped Wall Street’s third-quarter 2026 EPS estimates, but what investors took away from the two reports was quite different. Tesla tackled its biggest overhang by cutting its 2026 capital expenditure plan from $25 billion to $20 billion. Ford tightened its 2026 adjusted EBIT guidance to $10.5 billion-$11 billion, from $10 billion-$11 billion earlier, and said 2027 earnings should be roughly in line with this year’s.
Over the past month, Tesla shares have gained 14% while Ford has lost 1%. With third-quarter results now behind us, which stock is better positioned from here?
Image Source: Zacks Investment Research
The Case for Tesla
Tesla’s case rests on improving vehicle demand, healthier auto and energy margins and an AI roadmap with measurable milestones, even as high R&D spending weighs on operating profit.
Tesla’s deliveries and order backlog show demand holding up well. The company delivered 486,532 vehicles in its latest reported quarter, its second straight quarter above 480,000 units, and its passenger vehicle order backlog is the highest in four years. Management says demand is running well ahead of production, largely helped by rising FSD adoption. More than 75% of new North American deliveries included a paid FSD subscription at delivery. Recently, Latvia approved FSD, making it the 10th EU country to do so, according to Teslarati.
Gross margins are following volume. Automotive gross margin rose to 18.5% from 17% a year earlier. Energy storage deployments reached 13.7 GWh, up 10% year over year, while energy gross margin climbed to 33.1% from 20.4% in the second quarter of 2026. With CEO Elon Musk saying Megapack supply for 2027 is almost sold out, this business has strong forward visibility.
The AI story now has progress to show. Tesla began deploying Cybercabs in Austin in September 2026, and Musk says the fleet there has grown tenfold in roughly a month. Cumulative unsupervised Robotaxi miles rose eightfold sequentially to nearly 2 million. Management expects Robotaxi to contribute more meaningfully to revenues from next year.
The weak spot is operating profit, which contracted as R&D costs rose. It is expected to keep declining year over year in the coming quarters as Tesla funds its next growth cycle, and supply chain challenges persist. Still, the pressure is investment-led rather than demand-led. With strong demand, recovering gross margins, a return to positive free cash flow and tangible AI milestones, the narrative is getting stronger.
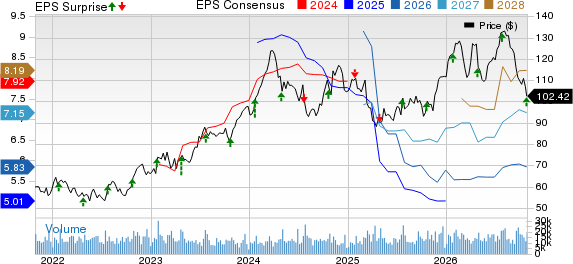
Tesla, Inc. Price, Consensus and EPS Surprise

Tesla, Inc. price-consensus-eps-surprise-chart | Tesla, Inc. Quote
The Case for Ford
Ford’s case rests on long-term franchise strength, but the near-term numbers are under pressure across all three of its segments.
The foundation is solid. Ford leads in trucks and SUVs, is expanding Super Duty capacity and is growing its software and parts businesses. Hybrid demand, an affordable EV platform and Ford Energy add runway, but these are long-term supports that do little for the near term.
The latest quarterly results showed the strain. At Ford Blue, wholesale units, revenues, EBIT and EBIT margin all declined. Discontinued models and disruptions linked to the Middle East conflict cut sales, and higher commodity costs weighed on profitability.
Ford Pro, a key earnings contributor, also saw margins slip. Third-quarter EBIT fell 16% year over year to $1.7 billion, and EBIT margin contracted to 9.4% from 11.4%. Management trimmed its full-year Ford Pro EBIT outlook to about $7 billion from $7-$7.5 billion earlier.
Ford Model e unit remains the biggest drag, with a $1.1 billion third-quarter EBIT loss, though $352 million narrower than a year ago. Revenues fell as the F-150 Lightning ended and Mach-E output dropped. Ford expects about $4 billion in 2026 losses, and higher 2027 spending on the Universal EV platform and Ford Energy pushes meaningful improvement to 2028.
Costs are the other worry. Commodity headwinds are now expected to approach $2.5 billion in 2026, about $500 million more than the earlier guidance, and higher fuel prices are lifting freight and energy costs. Ford expects U.S. industry pricing to rise about 100 basis points, but sustained inflation could absorb that benefit. Tariff uncertainty adds to the risk, and management sees about $2 billion of combined commodity, memory and logistics headwinds in 2027, which will require further efficiency gains to protect earnings.
Ford Motor Company Price, Consensus and EPS Surprise

Ford Motor Company price-consensus-eps-surprise-chart | Ford Motor Company Quote
Our Take: TSLA Has an Upper Hand Now
Tesla’s profit pressure comes from investing in growth but Ford’s comes from forces it can’t fully control. Tesla is spending more on R&D to build robotaxi and AI revenue streams, and it has already trimmed capex to protect cash flow. Ford’s pressure comes from outside its control, including commodities, tariffs and a loss-making EV unit that will not turn around before 2028.
Tesla’s demand, backlog and energy visibility suggest earnings growth next year. Ford is guiding to flat 2027 earnings, with fresh cost headwinds still to absorb.
Momentum in the business is building at Tesla, while Ford’s near-term stays clouded by cost pressure and EV losses. As such, Tesla looks better placed from here.
While Tesla currently carries a Zacks Rank #3 (Hold), Ford carries a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks’ Research Chief Names “Stock Most Likely to Double”
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren’t winners, but this one could far surpass earlier Zacks’ Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners Up
Ford Motor Company (F) : Free Stock Analysis Report
Tesla, Inc. (TSLA) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).