PACCAR Inc. PCAR reported third-quarter 2026 earnings of $1.61 per share, in line with the Zacks Consensus Estimate. The bottom line increased 43.8% from $1.12 in the year-ago quarter, supported by stronger truck profitability and favorable pricing.
Truck, Parts and Other revenues of $7.38 billion rose 20.8% year over year but missed the Zacks Consensus Estimate of $7.48 billion. Consolidated revenues, including financial services, increased 19% to $7.94 billion. Global truck deliveries climbed 25.7% to 40,100 units, while PACCAR Parts achieved record quarterly revenues.
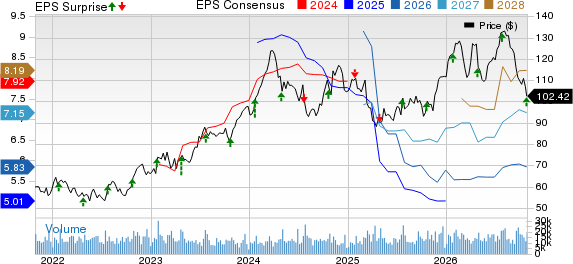
PACCAR Inc. Price, Consensus and EPS Surprise
PACCAR Inc. price-consensus-eps-surprise-chart | PACCAR Inc. Quote
PCAR’s Revenue Mix Favors Truck Sales
Truck revenues surged 27.9% year over year to $5.6 billion from $4.38 billion, reflecting higher deliveries and favorable pricing. Parts revenues increased 3.2% to a record $1.78 billion from $1.72 billion.
Financial Services revenues declined 1.1% to $558.9 million from $565.3 million. Intersegment eliminations and other totaled negative $4.8 million against a positive $0.5 million a year earlier.
Geographically, revenues from the United States and Canada advanced 26% to $5.02 billion. European revenues increased 1.6% to $1.7 billion, while revenues from other markets climbed 19.9% to $1.22 billion.
PACCAR’s Truck Profit Jumps on Strong Pricing
Truck pretax profit surged to $454.5 million from $102.5 million a year earlier, benefiting from favorable price realization and disciplined operating performance. Truck, Parts and Other gross margin reached 14.5%, supported by higher truck profitability.
U.S. and Canada deliveries increased to 23,800 units from 17,100. European deliveries improved to 10,400 units from 10,100, while other markets rose to 5,900 units from 4,700.
Management noted that supplier constraints restricted third-quarter deliveries as production rates increased. However, favorable truck pricing helped offset manufacturing inefficiencies, while price-cost remained positive during the quarter.
PCAR Parts Revenues Rise, but Profitability Declines
PACCAR Parts generated pretax income of $404.4 million compared with $410 million in the prior-year quarter, a decline of 1.4%. Profitability was affected primarily by product mix, as customers facing elevated operating costs concentrated on essential maintenance.
The business continued expanding through the TRP all-makes brand, Fleet Services and Managed Dealer Inventory programs. Its network includes 21 distribution centers supporting more than 2,000 DAF, Kenworth and Peterbilt locations and over 350 TRP stores.
For the first nine months, parts revenues increased to $5.24 billion from $5.14 billion, while pretax income declined to $1.22 billion from $1.25 billion.
PACCAR Financial Services Posts Higher Profit
Financial Services pretax income increased 9.4% year over year to $138.1 million from $126.2 million. Steady finance margins and improving used-truck prices supported profitability despite lower segment revenues.
Provision for losses on receivables declined to $28.6 million from $36.5 million. The business ended the quarter with a portfolio of 222,000 trucks and trailers and $22.5 billion in total assets. PacLease’s fleet totaled 37,000 vehicles.
For the first nine months, Financial Services pretax income rose to $377.7 million from $370.5 million. The segment issued $2.38 billion of medium-term notes during this period.
PCAR’s Cash Flow and Cost Trends
Within Truck, Parts and Other, cost of sales and revenues increased to $6.31 billion from $5.35 billion. Research and development expenses declined to $108.9 million from $111 million, while selling, general and administrative expenses decreased to $125.3 million from $140.3 million.
PACCAR generated $847.7 million in operating cash flow during the quarter. For the first nine months, operating cash flow totaled $2.52 billion compared with $3.27 billion a year earlier.
Cash and marketable securities totaled $9.24 billion as of Sept. 30, 2026, compared with $9.25 billion at Dec. 31, 2025.
PACCAR’s 2026 and 2027 Expectations
The company now projects 2026 U.S. and Canada Class 8 industry retail sales of 240,000-260,000 trucks. European above 16-ton registrations are expected at 300,000-320,000 units, while South American demand is forecast at 100,000-105,000 vehicles.
For 2026, capital expenditures are projected at $650-$700 million, down from the previous $700-$750 million estimate. Research and development spending is expected at $440-$460 million compared with the earlier $450-$480 million forecast.
PACCAR anticipates fourth-quarter deliveries of 41,000-43,000 trucks and Truck, Parts and Other gross margins of 14-15%.
For 2027, North American Class 8 sales are projected at 240,000-280,000 units, supported by fleet replacement and improving freight conditions. European demand is expected at 300,000-320,000 units, while South American sales are forecast at 105,000-115,000 vehicles.
PCAR currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Other Key Releases From the Auto Space
Genuine Parts Company GPC reported third-quarter 2026 adjusted earnings of $2.07 per share, missing the Zacks Consensus Estimate of $2.09. The bottom line increased 4.5% from $1.98 in the year-ago quarter. Revenues rose 4.2% year over year to $6.52 billion and surpassed the consensus estimate of $6.5 billion. Comparable sales increased 2.9%, led by strong Industrial demand. Genuine Parts ended September with $2.4 billion of liquidity, including $763 million in cash.
General Motors GM reported strong third-quarter 2026 results yesterday. Its earnings per share grew 32.2% year over year to $3.70 and topped the Zacks Consensus Estimate of $3.55. Revenues of $50.02 billion increased 3% year over year and outpaced the consensus mark of $48.21 billion. On a further encouraging note, General Motors raised its adjusted automotive free cash flow forecast to $11.5-$12.5 billion from $9.5-$11.5 billion and authorized a $20-billion multi-year share repurchase program.
Tesla TSLA reported third-quarter 2026 adjusted earnings of 48 cents per share, which beat the Zacks Consensus Estimate of 45 cents by 6.67%. However, earnings declined 4% from 50 cents in the year-ago quarter, reflecting higher operating expenses. Tesla’s revenues totaled $28.05 billion, down marginally from $28.1 billion a year ago. The metric surpassed the Zacks Consensus Estimate of $27.78 billion by 0.96%. Tesla has trimmed its 2026 capital expenditure outlook to approximately $20 billion from $25 billion guided earlier.
Zacks’ Research Chief Names “Stock Most Likely to Double”
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren’t winners, but this one could far surpass earlier Zacks’ Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners Up
PACCAR Inc. (PCAR) : Free Stock Analysis Report
Genuine Parts Company (GPC) : Free Stock Analysis Report
General Motors Company (GM) : Free Stock Analysis Report
Tesla, Inc. (TSLA) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).