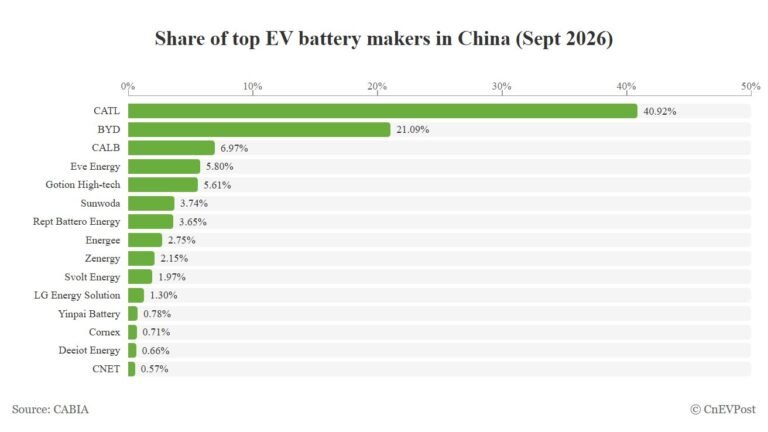
| Company | Market Share (%) | Installations (GWh) |
|---|---|---|
| CATL | 39.1% | 389.2 |
| BYD | 15.2% | 150.9 |
| LGES | 8.2% | 81.9 |
| Gotion | 5.1% | 50.3 |
| CALB | 5.0% | 50.1 |
| Eve Energy | 3.6% | 36.0 |
| Panasonic | 3.6% | 35.6 |
| SK On | 2.8% | 28.3 |
| Svolt Energy | 2.6% | 25.7 |
| Rept | 2.4% | 24.2 |
| Other | 12.3% | 122.4 |
- The 7 Chinese companies in the top 10 held a combined 73.0% share of the global EV battery market, up 3.5 percentage points from a year earlier.
- CATL and BYD held a combined 54.3% share, while SK On and Panasonic were the only companies in the top 10 to post declines in battery installations.
CATL (HKEX: 3750) and BYD (HKEX: 1211) continued to dominate the global electric vehicle (EV) battery market in the first 9 months of 2026, together accounting for more than half of the market.
Global EV battery usage totaled 994.5 GWh in January-September, up 19.7% year-on-year, according to data released on Monday by South Korean market research firm SNE Research.
Battery installations reached a monthly record of 145.1 GWh in September, though year-on-year growth slowed to 15.8%, below the cumulative growth rate. The figures cover battery electric vehicles, plug-in hybrids and conventional hybrids.
CATL retained the top spot with 389.2 GWh of battery installations, up 24.9% year-on-year, outpacing the overall market. Its global share rose to 39.1% from 37.5% a year earlier, but slipped 0.3 percentage points from 39.4% in January-August.
Second-ranked BYD recorded battery installations of 150.9 GWh, up 7.4% year-on-year. Its share fell to 15.2% from 16.9% a year earlier, though it edged up from 15.1% in January-August.
The 2 companies held a combined share of 54.3%, little changed from 54.4% a year earlier but down from 54.6% in January-August.
CATL continued to expand its overseas automaker customer base, while BYD’s battery supply remained largely tied to its own vehicle sales, widening the gap between their growth rates to 17.5 percentage points, SNE Research said.
BYD’s slowdown stemmed from the Chinese market. SNE Research said BYD’s EV sales in China fell 32.9% year-on-year, while its battery installations in the country declined 7.1% to 104.9 GWh from 112.9 GWh.
By contrast, BYD’s battery installations outside China rose 66.8% year-on-year to 45.9 GWh from 27.5 GWh. Its overseas vehicle sales totaled about 180,000 in September, more than doubling from a year earlier and accounting for nearly 40% of total sales.
South Korea’s LG Energy Solution (LGES) ranked third with 81.9 GWh, up 0.7% year-on-year. Its share fell to 8.2% from 9.8% a year earlier.
LGES continued to supply Tesla (NASDAQ: TSLA), GM, Hyundai Motor Group and Volkswagen, but its growth lagged far behind the broader market.
Its battery installations in Europe rose 13.2% year-on-year to 38.6 GWh, while those in Asia increased 49.4% to 11.1 GWh. However, installations in North America fell 44.9% to 16.5 GWh from 29.9 GWh, offsetting most of those gains.
China’s Gotion High-tech (SZSE: 002074) climbed to fourth place with 50.3 GWh, up 48.1% year-on-year. Its share rose to 5.1% from 4.1% a year earlier.
Gotion edged past CALB (HKEX: 3931) by just 0.2 GWh. CALB ranked fifth with 50.1 GWh, up 27.1% year-on-year, while its share increased to 5.0% from 4.7%.
China’s Eve Energy (SZSE: 300014) ranked sixth with 36.0 GWh, up 60.4% year-on-year, overtaking Japan’s Panasonic. Its share rose to 3.6% from 2.7%.
Panasonic slipped to seventh place with 35.6 GWh, down 0.8% year-on-year, while its share fell to 3.6% from 4.3%. Its installations came mainly from Tesla models in North America, with that volume declining slightly to 34.9 GWh.
South Korea’s SK On ranked eighth with 28.3 GWh, down 18.1% year-on-year, the steepest decline among the top 10. Its share fell to 2.8% from 4.2%. Its North American installations dropped 46.7% to 7.6 GWh from 14.2 GWh.
China’s Svolt Energy ranked ninth with 25.7 GWh, up 37.9% year-on-year, while its share rose to 2.6% from 2.2%.
China’s Rept Battero Energy (HKEX: 666) remained in tenth place as its battery installations surged 118.7% to 24.2 GWh. Its share rose to 2.4% from 1.3%. It led eleventh-ranked Sunwoda, which recorded 23.0 GWh, by about 1.2 GWh.
The 7 Chinese companies in the top 10 held a combined share of 73.0%, up 3.5 percentage points from 69.5% a year earlier, but slightly below the 73.3% recorded in January-August.
The 3 South Korean companies held a combined share of 12.6%, down 4.1 percentage points year-on-year.
By region, battery installations in China rose 16.2% year-on-year to 567.8 GWh. Europe recorded growth of 33.1%, while Asian markets outside China grew 74.1% and South America expanded 176.8%. North America, however, saw installations fall 24.3% to 85.9 GWh.
The share of lithium iron phosphate (LFP) batteries rose to 57.7% from 52.5% a year earlier. Average battery capacity per vehicle increased 11.2% year-on-year to 39.7 kWh from 35.7 kWh, helping battery installations grow faster than vehicle sales.

CATL remained the leader, but its market share gap with BYD narrowed for the fourth consecutive month.