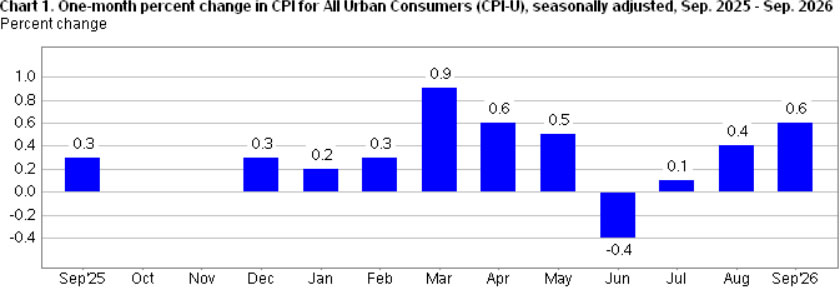
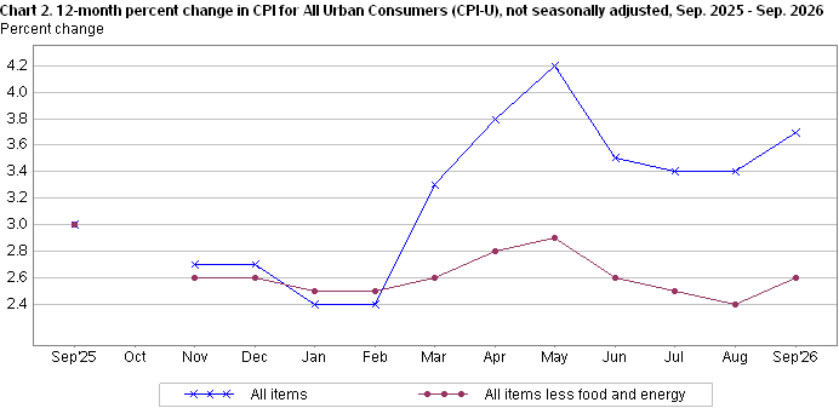
US core inflation exceeded expectations in September, indicating that underlying price pressures are proving more persistent than anticipated even as surging energy costs drive headline inflation higher. Core CPI rose 0.3% mom, unchanged from August but above expectations of 0.2%. On an annual basis, core inflation accelerated from 2.4% to 2.6% yoy, exceeding forecasts of 2.5%. Headline CPI increased from 0.4% to 0.6% mom, matching expectations, while the annual rate climbed from 3.4% to 3.7% yoy, slightly above consensus of 3.6%. The combination suggests that September’s inflation acceleration cannot be attributed entirely to higher energy prices.
Underlying price pressures strengthened across both goods and services. Core goods inflation accelerated from 0.1% to 0.3% mom, supported by used cars and trucks, which rose 0.7%, and apparel, which increased 0.3%. Core services excluding energy also accelerated from 0.3% to 0.4% mom, with shelter inflation rising from 0.3% to 0.4%. Owners’ equivalent rent increased 0.3%, while lodging away from home climbed 2.0%. Additional pressure came from recreation, which rose 0.5%, transportation services at 0.6%, and airline fares at 1.2%. The broader increases suggest that underlying inflation has yet to establish a sustained moderation, even though some individual components are showing more restrained price growth.
Meanwhile, energy remained the dominant contributor to headline inflation, with the energy index accelerating from 2.1% to 5.2% mom. Gasoline prices surged 9.1%, accounting for more than half of the monthly headline increase, while fuel oil prices jumped 15.3%. Energy inflation reached 20.4% yoy, reflecting the substantial impact of elevated fuel costs. Food provided some offset, with prices unchanged on the month as grocery costs declined 0.1%. The key concern is that energy-driven headline inflation is now accompanied by firmer underlying price pressures, rather than being confined to a single volatile category. While the report does not establish that higher energy costs are already feeding into broader prices, September’s core inflation surprise suggests that disinflation remains vulnerable to setbacks.
Data Summary — US September 2026 CPI
Headline Inflation Data
| Indicator | August | September | Consensus |
|---|---|---|---|
| Headline CPI m/m | +0.4% | +0.6% | +0.6% |
| Headline CPI y/y | +3.4% | +3.7% | +3.6% |
| Core CPI m/m | +0.3% | +0.3% | +0.2% |
| Core CPI y/y | +2.4% | +2.6% | +2.5% |
Inflation Components
Seasonally adjusted monthly changes
| Component | August | September |
|---|---|---|
| Energy | +2.1% | +5.2% |
| Gasoline | +3.9% | +9.1% |
| Fuel Oil | +10.1% | +15.3% |
| Food | +0.1% | 0.0% |
| Food at Home | 0.0% | -0.1% |
| Core Goods | +0.1% | +0.3% |
| Core Services | +0.3% | +0.4% |
| Shelter | +0.3% | +0.4% |
| Owners’ Equivalent Rent | +0.2% | +0.3% |
| Used Cars and Trucks | +0.4% | +0.7% |
| Recreation | 0.0% | +0.5% |
| Airline Fares | +2.7% | +1.2% |
Source: US Bureau of Labor Statistics, September 2026 CPI release.
Key Takeaways
- Core inflation exceeds expectations: Core CPI held at 0.3% mom, above forecasts of 0.2%, while the annual rate accelerated from 2.4% to 2.6%, exceeding expectations of 2.5%.
- Underlying pressures extend beyond energy: Core goods inflation accelerated from 0.1% to 0.3% mom, while core services excluding energy strengthened from 0.3% to 0.4%. The increases suggest underlying disinflation is not progressing as expected.
- Shelter and services contribute to core inflation: Shelter inflation accelerated from 0.3% to 0.4% mom, while used vehicles, recreation and transportation services also recorded price increases.
- Gasoline drives headline inflation higher: Headline CPI accelerated from 3.4% to 3.7% yoy, slightly above consensus. Gasoline prices surged 9.1% mom, accounting for more than half of the monthly headline increase.
- Inflation outlook becomes more challenging: Energy remains the dominant source of headline pressure, but the core CPI surprise shows inflation is not confined to gasoline. The report does not establish second-round energy effects, although broader underlying pressures warrant attention.