United States Antimony has seen its share price swing sharply in recent years, which puts a spotlight on whether the current US$3.10 level lines up with the sales the business is actually producing. The question for investors is whether the recent price reset is giving a realistic signal about the value of those sales or stretching them.
- Over the past 3 years the stock has delivered a very large gain. This makes the relationship between its current valuation and its underlying sales a crucial issue for anyone considering the shares today.
- With the business model tied to commodity-linked products and the costs required to process and supply them, any change in pricing, volumes or operating efficiency can shift how much investors are effectively paying for each dollar of revenue.
- There is a second opinion on United States Antimony worth weighing. See what analysts think United States Antimony’s shares could be worth.
For investors, the debate is whether United States Antimony’s current share price is appropriately grounded in the scale and quality of its sales today.
If you are weighing whether United States Antimony’s US$3.10 share price lines up with its sales, it can help to compare that same question across 35 high quality undervalued stocks.
Has United States Antimony Run Too Far on Sales?
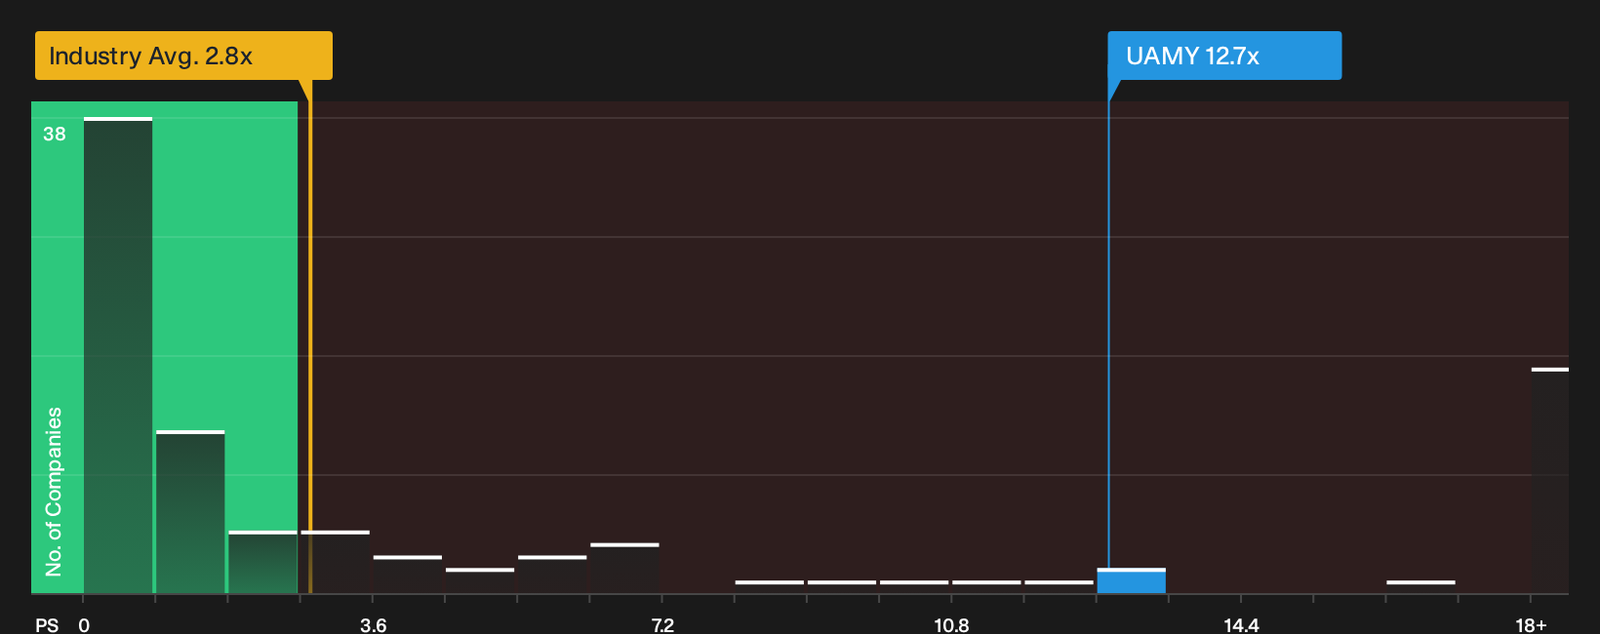
P/S is often a cleaner lens for United States Antimony because reported earnings can swing around its commodity exposure while revenue tends to move more directly with volumes and pricing. On this yardstick, the stock trades on a P/S of 12.7x, compared with an industry average of about 2.8x and a peer group closer to 5.0x.
The Fair Ratio model, which adjusts for the company’s growth profile, margins, size and risk, indicates that United States Antimony is pricing well above the level this framework would usually point to for its fundamentals. The gap is large enough that the output looks less like a fine tuned target and more like a warning that the shares screen as very expensive on sales compared with similar metals and mining businesses. For anyone considering the stock at US$3.10, the key question is whether future execution and revenue quality justify paying this kind of premium to each dollar of current turnover. Explore the numbers behind United States Antimony’s P/S valuation.

The United States Antimony Narrative: What Would Justify Today’s Price?
Simply Wall St Narratives take the valuation puzzle around United States Antimony and spell out the specific paths on growth, margins and earnings that would need to play out for the shares to be worth materially more or less than the current price, using the Community page to set out clear scenarios that sit behind a single ratio or model output so you can see exactly which future it assumes and track whether that still looks realistic over time.
One of the top community narratives on United States Antimony: 72% undervalued
“Expanded processing capacity, new ore sources, and government engagement position the company for sustained growth, supply security, and potential long-term premium contracts…”
Discover why this Narrative puts United States Antimony at 72% undervalued.
One more United States Antimony factor that could change the story
Price tags and sales multiples only tell part of the story, because the people setting priorities and the way they are rewarded can tilt outcomes in ways the ratios miss. See who runs United States Antimony and how they are paid.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com