The Morning Bull – UK Market Morning Update Thursday, 5 Nov 2026
UK stocks are set for a cautious open as investors focus squarely on the Bank of England. The expected rate hike is the single story that matters for the FTSE this morning.
Markets are working with a consensus that the BoE lifts Bank Rate from 3.75% to 4%. That would mark the first increase in more than three years, with policymakers responding to higher inflation pressures linked to the Iran conflict and energy costs.
A higher policy rate raises borrowing costs for households and companies, which can squeeze consumer demand and investment plans. Interest sensitive areas like property, utilities and highly leveraged businesses often feel this most quickly through refinancing costs and weaker pricing power.
The unresolved question is simple: does the BoE signal this is a single inflation fighting move, or hint at a series of increases in the Monetary Policy Report and vote split, which would force investors to reassess the entire UK earnings outlook?
Stocks to Watch Before the Opening Bell
Marks and Spencer Group (MKS)
Marks and Spencer Group faces an estimated £150 million rise in costs this year after the Labour 2024 Budget. The CEO describes the package as one of the biggest tax grabs in history, pointing to higher National Insurance, the National Minimum Wage and new packaging charges. Readers may wish to monitor how the retailer adjusts pricing, investment plans and cost saving efforts.
Metro Bank Holdings (MTRO)
Metro Bank Holdings reported 37% year on year growth in lending across its target segments in the third quarter of 2026, with exit net interest margin at 3.45%, up 42 basis points. The group reaffirmed guidance, including RoTE targets of more than 13% in Q4 2026 and over 18% in 2028. A key focus is delivery against those targets.
SSE (SSE)
SSE is progressing with energy infrastructure plans, opening a new Glasgow office for around 640 staff as part of a £29 billion investment programme. The firm is also leading the 3.6 GW Dogger Bank Wind Farm and has agreed a second turbine installation vessel for Dogger Bank C. Attention now turns to execution milestones and any timing or cost updates.
Top Movers
-
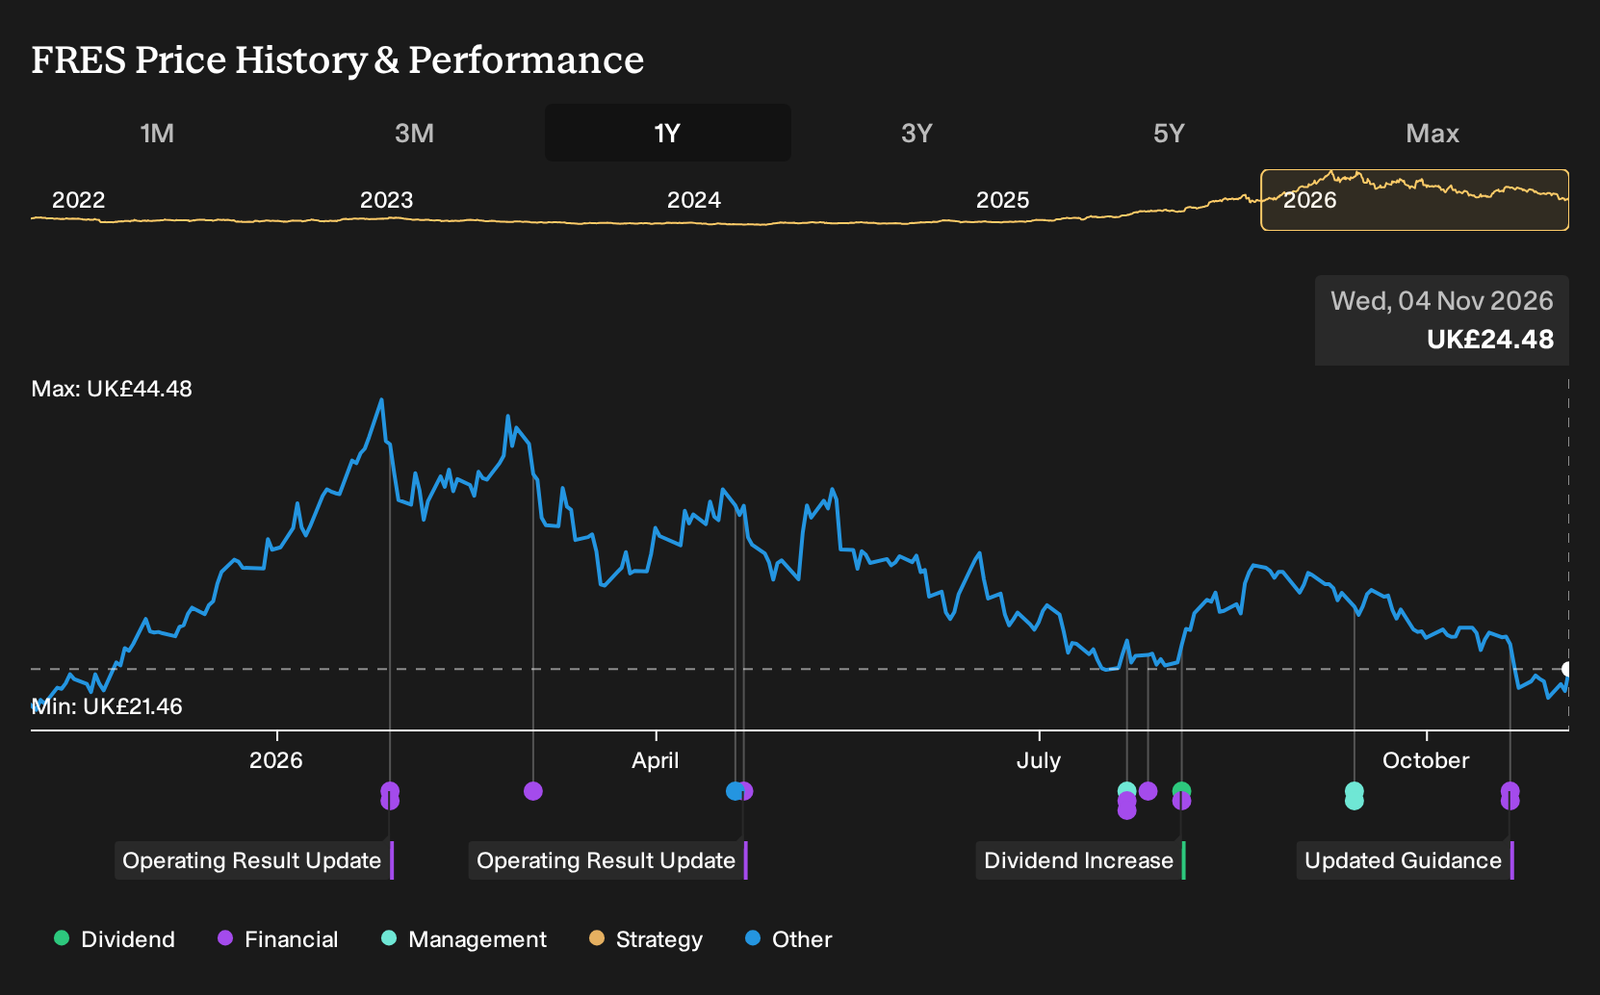
Fresnillo (LSE:FRES) jumped 7.09% as investors reacted to stronger precious metals prices following the US midterm outcome.
-
Smith & Nephew (LSE:SN.) climbed 6.49% after investors assessed reduced guidance, an orthopaedics review and ongoing share buybacks.
-
Associated British Foods (LSE:ABF) rose 6.37% as the market absorbed full year results and the planned Primark demerger.
Top Losers
-
Weir (LSE:WEIR) fell 9.58% after investors focused on softer organic order growth versus peers, despite reaffirmed guidance.
-
Ithaca Energy (LSE:ITH) declined 8.11%.
-
Serica Energy (LSE:SER) fell 6.47% as traders weighed the multi well UK drilling contract and future capital commitments.

On The Radar
UK rates and growth data line up with a busy run of domestic earnings, giving the FTSE a direct read on borrowing costs, household demand and corporate pricing power.
- BoE Interest Rate Decision, Thu 5 Nov. Holding or lifting Bank Rate away from the current 3.75% level would immediately affect funding costs for UK banks, real estate and utilities, as well as the direction of sterling against the dollar.
- S&P Global UK Construction PMI, Thu 5 Nov. A reading near the prior 46.1 mark keeps the sector in contraction territory, which matters for housebuilders and building materials suppliers that rely on project pipelines and mortgage availability.
- BT Group, Thu 5 Nov. Q2 2027 results put the focus on revenue trends in UK broadband and mobile, along with any guidance on cost inflation that shapes how the telecom handles high capital spending and dividend plans.
- National Grid, Thu 5 Nov. First half 2027 figures spotlight regulated returns and investment outlays in UK energy networks, which tie directly into how higher interest rates feed through to allowed returns and future bill levels.
- UK GDP data batch, Thu 12 Nov. The Q3 GDP forecasts of 0.4% quarter on quarter and 1.7% year on year, plus September monthly GDP at 0.2%, will influence views on how long tighter policy can coexist with steady employment and consumer spending.
Sector & Industry Watch
Energy: Rate nerves meet oil headlines
Energy and Oil and Gas have slipped over the past week, with both sectors down a little over 5% despite strong year to date and 12 month gains. News around Shell and BP, LNG disruption linked to the Iran conflict and fresh crude price moves keeps short term trading closely tied to commodity headlines.
If you hold fuel producers, the swing factor today is the Bank of England decision because a higher base rate can affect project finance costs for oil groups as much as day to day moves in Brent.
Consumer Staples: Grocers juggle costs and demand
Consumer Staples and Food, Beverage & Tobacco have climbed over the past week, helped by steady demand for everyday goods even as households manage higher borrowing and energy bills. Marks and Spencer’s £150 million cost hit from higher UK taxes and wages, plus stronger revenue guidance at Coca Cola HBC, show how pricing power and cost control differ across the sector.
If you rely on grocers or drinks stocks for defensive income, focus on upcoming trading statements for clues on how far companies can raise shelf prices without losing shoppers because that margin story often feeds directly into dividend decisions.
Healthcare: Pharma strength offsets rate worries
Healthcare and Pharmaceuticals & Biotech have logged solid seven day gains, with AstraZeneca helping lift the group and sector P/Es still a little below three year averages. These businesses often move more on trial results and regulator calls than on UK rate shifts, which can make them a useful counterweight on big macro days.
If healthcare features in your ISA or pension, the key event to watch is AstraZeneca’s clinical trial update flagged for tomorrow since any surprise on its pipeline can quickly reshape sentiment toward the wider UK drug sector.
Metals and Mining: Softer week as copper stories build
Metals and Mining and the broader Materials group have eased over the past seven days, with both sectors down a few percent even though 12 month returns remain in the mid 20s. Headlines range from Capital Limited’s upgraded revenue guidance to copper supply issues at Kamoa Kakula and a sharp jump in gold producers such as Fresnillo and Pan African following the US midterms.
If miners are in your portfolio, the single macro print to keep an eye on is Germany’s factory orders release because it feeds directly into expectations for European industrial demand that underpin copper, iron ore and gold revenue for UK listed groups.
Real Estate: Recent rebound tested by rate call
Real Estate has picked up over the past week, with a seven day gain of just under 3% adding to a stronger month helped by interest in flexible office providers. That improvement still sits beside earlier earnings pressure and questions over refinancing as funding costs move higher for landlords, student housing operators and logistics owners.
If you own REITs or house heavy funds, today’s combination of the Bank of England decision and tomorrow’s Lloyds House Price Index matters because the path of mortgage rates and house values together shapes rental prospects, portfolio valuations and how easily property groups can extend their debt maturities.
How To Act On Today’s Market
If steady dividends are your focus while the Bank of England weighs another rate hike, start with this list of 216 dividend fortresses as a way to stress test your income ideas.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com