Key Points
-
Tesla has delivered 1,324,681 vehicles so far in 2026, up around 9% year over year.
-
Around 311,500 fourth-quarter deliveries would be enough for Tesla to pass its 2025 total.
-
Tesla shares trade at around 165 times next year’s expected earnings.
- These 10 stocks could mint the next wave of millionaires ›
Tesla (NASDAQ:TSLA) delivered 486,532 vehicles in the third quarter of 2026, the EV maker said on Friday, Oct. 2. That was off 2% from a year earlier, when U.S. buyers raced to get a $7,500 federal tax credit before it ended and Tesla posted its all-time quarterly record of 497,099.
The more important figure is the running total. Through three quarters, Tesla has delivered 1,324,681 vehicles, around 9% more than by this time in 2025. This puts the company on pace for its first annual increase in deliveries since 2023, after two straight years of declines.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
Investors seemed to like the news. As I write, shares trade near $371, up about 5% since Thursday’s close.
But I don’t think a return to delivery growth helps the stock as much as that year-to-date number could suggest.
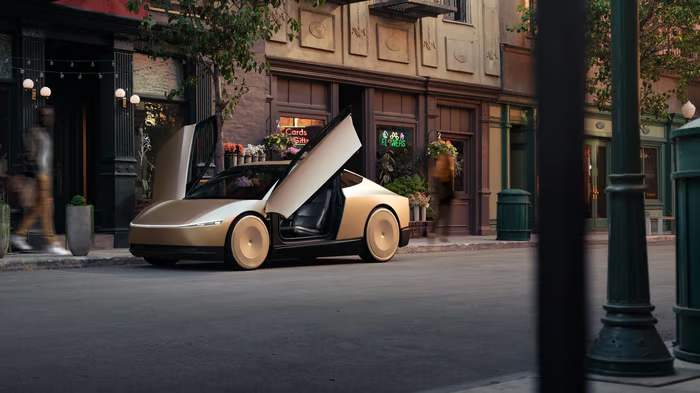
Image source: Tesla.
A low bar
To beat 2025’s total of 1,636,129 deliveries, Tesla needs only about 311,500 more in the fourth quarter. It delivered 418,227 vehicles in the fourth quarter of 2025. So its deliveries could drop around 25% year over year in the last three months of 2026, and it’d still finish with a growth year.
Showing how much cushion Tesla has, even its weakest quarter this year cleared that bar easily. First-quarter deliveries totaled 358,023, a gain of 6% from a year earlier. Growth then sped up to 25% in the second quarter, when deliveries hit 480,126. And the count fell just 2% in the third quarter, versus last year’s tax-credit rush.
So, without a big disruption, the EV maker’s two-year delivery slide looks all but over.
How many cars might Tesla deliver in 2026?
Tesla made around 50,000 more vehicles than it delivered in the first quarter, then sold down that extra inventory over the next two quarters. Through September, it has produced 1,324,535 vehicles and delivered 1,324,681 — almost equal totals.
With the extra inventory gone, fourth-quarter deliveries will probably depend on what the plants can make. Production has climbed every quarter this year, from 408,386 vehicles in the first quarter to 451,758 in the second and 464,391 in the third. But Tesla has said that battery pack capacity is the biggest thing holding back faster vehicle production.
If Tesla delivers about as many vehicles in the fourth quarter as it made in the third, it would end 2026 with around 1.79 million deliveries. That would be up around 9% over 2025 — yet almost exactly the same as the 1,789,226 vehicles Tesla delivered in 2024. And beating its 2023 record of 1,808,581 would take about 484,000 fourth-quarter deliveries, which is roughly what Tesla did in the third quarter with help from inventory.
In short, 2026 looks more like a recovery to where Tesla was two years ago than a step into new territory.
Tesla’s stock needs more than car sales
This recovery would be easier to get excited about if Tesla’s profits were coming back with it, and so far they aren’t.
For 2024, the last year Tesla delivered around 1.79 million vehicles, its earnings per share were $2.29 on a non-GAAP (adjusted) basis, off around 27% from $3.12 in 2023. Adjusted earnings per share then slid another 28% in 2025, to $1.66. In the past four reported quarters, the number totaled $1.74. That’s still around 24% under 2024’s level, even though Tesla delivered only about 2% fewer vehicles in that span than it did in all of 2024. Tesla will release third-quarter results on Oct. 21, and that report should show if this year’s extra cars are earning more.
Meanwhile, the stock prices in much more than a car business getting back to its 2024 volume. At around $371, Tesla trades at more than 210 times its adjusted earnings in the last four quarters and about 165 times next year’s expected earnings. A price-to-earnings ratio like that assumes profits grow many times over, and single-digit delivery growth can’t do that on its own.
What the market is arguably paying for is Tesla’s self-driving ambitions, including its Robotaxi service and the Cybercab it started building earlier this year.
Is a growth year enough to make Tesla stock a buy? Not at this price, in my view.
Sure, the delivery slide looks finished, and Tesla doesn’t need a big fourth quarter to prove it. But at around 165 times next year’s expected earnings, I think the stock’s still too pricey for a car business that’s mainly getting back to where it was in 2024.
Don’t miss this second chance at a potentially lucrative opportunity
Ever feel like you missed the boat in buying the most successful stocks? Then you’ll want to hear this.
On rare occasions, our expert team of analysts issues a “Double Down” stock recommendation for companies that they think are about to pop. If you’re worried you’ve already missed your chance to invest, now is the best time to buy before it’s too late. And the numbers speak for themselves:
- Nvidia: if you invested $1,000 when we doubled down in 2009, you’d have $608,222!*
- Apple: if you invested $1,000 when we doubled down in 2008, you’d have $63,654!*
- Netflix: if you invested $1,000 when we doubled down in 2004, you’d have $361,650!*
Right now, we’re issuing “Double Down” alerts for three incredible companies, available when you join Stock Advisor, and there may not be another chance like this anytime soon.
*Stock Advisor returns as of October 4, 2026.
Daniel Sparks has clients with positions in Tesla. The Motley Fool has positions in and recommends Tesla. The Motley Fool has a disclosure policy.