TL;DR: GBP/CAD faces back-to-back inflation tests, Canada CPI today and UK CPI on Wednesday, after both central banks resumed hiking without giving the cross a direction. With broadly parallel rate paths priced, only a surprise large enough to shift one side’s policy outlook relative to the other’s is likely to break the 1.8604–1.9042 range.
Why Are Rate Hikes Not Moving GBP/CAD Out of Its Range?
GBP/CAD faces two important inflation tests this week after the Bank of Canada and Bank of England both resumed raising interest rates, yet neither move was enough to establish a decisive direction for the cross. BoC raised its overnight rate by 25bps to 2.50% on October 28, followed by BoE’s 25bps increase to 4.00% on November 5. Despite the tightening on both sides, GBP/CAD has remained confined to a broad consolidation between 1.8604 and 1.9042, trading around 1.8851 in early Monday trading.
Canada’s October CPI, due today at 13:30 GMT, and the UK’s inflation report on Wednesday at 07:00 GMT will test whether broadly synchronized policy expectations can finally diverge enough to break that range.
Follow today’s Canada CPI release and Wednesday’s UK CPI reaction on the ActionForex Telegram channel.
Canada CPI: Greater Scope for Near-Term BoC Repricing
The immediate focus is Canada, where markets have greater room to reassess the near-term tightening outlook. OIS pricing indicates approximately 13.4bps of additional tightening by the December 9 BoC meeting, followed by 29.6bps by January 27 and 43.6bps by March 3. By October 2027, the curve implies 78.7bps of cumulative additional increases, equivalent to slightly more than three quarter-point hikes.
- December 9: about 13.4bps of additional tightening priced
- January 27: about 29.6bps
- March 3: about 43.6bps
- October 2027: about 78.7bps (slightly more than three quarter-point hikes)
These expectations leave the December decision relatively open, making today’s inflation figures particularly important. Headline CPI accelerated from 3.0% to 3.1% yoy in September, while the median and trimmed-mean measures stood at 1.9% and 1.8%, respectively. October headline inflation is expected to rise to 3.2%, with CPI median projected at 2.0%.
A stronger-than-expected reading, particularly in underlying inflation, could reinforce expectations of another December hike and support CAD. Conversely, softer inflation could prompt markets to reduce near-term tightening expectations, weighing on the Canadian currency.
UK CPI: December Largely Priced, 2027 Path at Stake
The UK’s inflation outlook presents a different challenge for market pricing. September headline CPI accelerated from 3.1% to 3.5% yoy, while core inflation increased from 2.6% to 2.8% and services inflation rose from 3.4% to 3.7%. October headline CPI is expected to reach 3.6%, with core inflation projected at 2.8%.
OIS markets already imply approximately 19.5bps of tightening at the December 17 BoE meeting, equivalent to a 78% probability of a 25bps increase under a simple binary assumption. Cumulative tightening expectations rise to 37.7bps by February, 53.3bps by March and 91.2bps by November 2027, implying a policy rate near 4.91%.
- December 17: about 19.5bps (about 78% probability of a 25bps hike)
- February: about 37.7bps
- March: about 53.3bps
- November 2027: about 91.2bps (policy rate near 4.91%)
With a December increase substantially priced, Wednesday’s inflation report may have greater significance for the expected extent of tightening through 2027 than for the immediate decision alone. A persistent acceleration in underlying inflation could validate the current rate path or encourage further repricing, while softer readings would challenge expectations for nearly four additional quarter-point increases.
Parallel OIS Paths Keep GBP/CAD in Balance
The comparison between the two OIS curves helps explain GBP/CAD’s lack of a sustained directional move. Markets currently price 91.2bps of additional BoE tightening over approximately the coming year, against 78.7bps for BoC, leaving a relatively modest 12.5bps difference between the cumulative increases at the final compared meetings.
Both curves have also shifted higher over the past week, limiting the change in the relative monetary policy outlook. The UK advantage is somewhat larger at several intermediate meetings, but neither currency enjoys an overwhelming advantage from incremental rate expectations.
Consequently, the critical issue is not simply whether inflation exceeds forecasts, but whether one country’s data generates a substantially larger policy repricing than the other’s.
Two CPI Releases, Two Routes Out of the Range
The sequence of releases creates an asymmetric opportunity. Canada’s CPI arrives first, with greater scope to alter the pricing of its December decision. A downside surprise could weaken CAD and push GBP/CAD toward the upper boundary of its consolidation before Wednesday’s UK CPI. If British inflation then exceeds expectations, the combined repricing could provide the catalyst for an upside breakout.
Conversely, stronger Canadian inflation followed by softer UK figures would favor a decline toward range support. UK labour data on Tuesday and retail sales releases from both countries on Friday provide additional evidence on domestic economic conditions.
However, with both central banks already expected to tighten further, modest surprises may generate volatility without establishing a lasting directional trend. A decisive breakout would likely require a meaningful change in the relative policy outlook rather than an isolated inflation surprise.
ActionForex’s Technical View: GBP/CAD, Consolidation Within a Larger Uptrend
Daily Outlook: 1.8795 EMA Holds the Near-Term Key
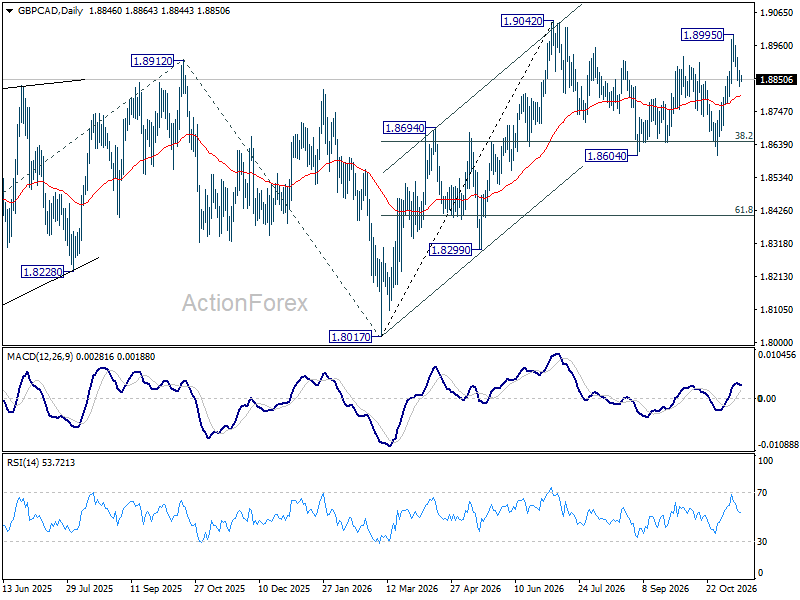
GBP/CAD continues to consolidate after reaching 1.9042 in July. The decline from that high to 1.8604 is viewed as the first leg of the consolidation, with the subsequent rise forming the second leg.
A sustained break below the 55-day EMA, currently around 1.8795, would suggest that the third leg has begun, opening another decline toward the 38.2% retracement of 1.8017 to 1.9042 at 1.8650. Strong support around 1.8604 should contain the downside under this scenario.
On the upside, a break above 1.8995 would bring another test of 1.9042. A decisive break through that resistance would invalidate the current consolidation interpretation and signal resumption of the larger uptrend.
From the early Monday level of 1.8851, the upper boundary is approximately 191 pips away, compared with 247 pips to 1.8604. Nevertheless, the proximity of the 55-day EMA means a relatively modest inflation surprise could trigger an important short-term move without necessarily breaking the broader range.
Weekly Outlook: Bullish Structure Favors Eventual Upside Break
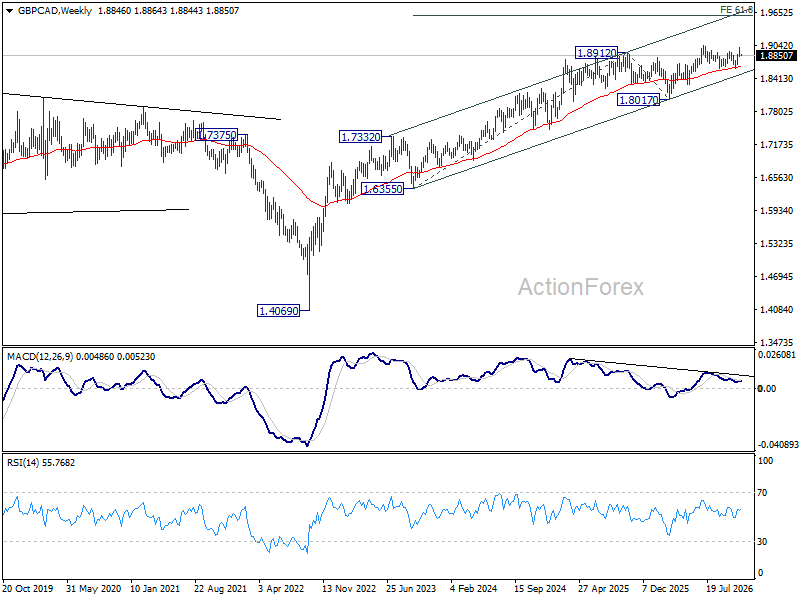
The longer-term outlook remains constructive, with the uptrend from the 2022 low at 1.4069 intact within a rising channel. The 55-week EMA, currently near 1.8664, provides additional support around the 1.8604–1.8650 zone, reinforcing the view that the current consolidation is corrective within the larger advance.
An eventual upside breakout remains favored, with the 61.8% projection of 1.6355 to 1.8912 from 1.8017 targeting 1.9597.
However, a decisive break below the 1.8604–1.8650 support zone, accompanied by sustained trading beneath the 55-week EMA, would raise the possibility that the entire uptrend from 1.4069 is undergoing a larger correction, potentially exposing 1.8017.
For now, Canada’s inflation release has greater potential to reshape immediate rate expectations, while the UK figures will determine whether the relative tightening outlook shifts further in Sterling’s favor. A sustained GBP/CAD breakout will likely require more than a temporary inflation surprise: it will need a meaningful divergence in the policy paths priced for the two central banks.
Key Takeaways
- GBP/CAD has stayed in a 1.8604–1.9042 range, trading around 1.8851, despite BoC (2.50%) and BoE (4.00%) hikes.
- Canada’s October CPI (13:30 GMT today) has greater scope to change near-term pricing, with about 13.4bps of BoC tightening priced for December 9 and 78.7bps by October 2027.
- UK CPI (Wednesday, 07:00 GMT) matters more for the 2027 path, since December is largely priced (about 78%) and 91.2bps is priced by November 2027.
- The 12.5bps gap between the two cumulative paths is modest, so a breakout needs a relative repricing rather than an isolated surprise.
- Support lies at the 55-day EMA near 1.8795, then 1.8650 and 1.8604, while resistance is 1.8995 and 1.9042, with 1.9597 the larger upside target.
Stay ahead of Canada and UK CPI and the next move in GBP/CAD—join the ActionForex Telegram channel for regular market updates and analysis.