Quick overview
- AMD is currently trading near $550, down about 3.7% after a significant 45% rebound driven by strong Q3 results and Nvidia’s CEO change.
- The company reported a record Q3 revenue of $13.4 billion, with a notable 97% increase in Data Center revenue.
- AMD’s 2027 outlook anticipates over 80% revenue growth, primarily from server CPU and data center AI revenue.
- Key technical levels to watch include support at $547.89 and resistance at $593.56, with potential targets of $519.64 and $625.61.
Quick Answer: AMD (NASDAQ: AMD) is trading near $550 on Friday, November 13, down about 3.7% as it gives back part of a 45% rebound in five sessions. The rally from $404.40 was driven by strong Q3 results, a 2027 outlook for more than 80% revenue growth and Nvidia’s surprise CEO change. On the 4-hour chart, the stock was rejected at the $593.56 trendline and is now testing $547.89 support.
My view: cautiously bearish below $593.56. A 4-hour close below $547.89 targets $519.64 and $496.48, while a break above the trendline opens $625.61.
A 45% Rebound in Five Sessions
AMD closed at $585.30 on Thursday, November 12, up 5.86% on the day and about 44.7% above its November 5 close of $404.40. That November 5 close came after a 17.26% one-day drop during an AI-wide sell-off. Thursday’s gain came after Nvidia confirmed that Jensen Huang had resigned as CEO and named CFO Colette Kress interim chief executive, and investors moved toward Nvidia’s rivals. William Blair upgraded AMD to Outperform, citing Nvidia’s leadership uncertainty and Intel’s supply challenges.
Q3 Results Beat, and PCs Held Up
Third-quarter revenue rose 45% to a record $13.4bn, and non-GAAP EPS, which strips out one-off items, rose 74% to $2.09, AMD reported. Both beat consensus forecasts of $13.09bn and $1.95. Data Center revenue nearly doubled, up 97% to $8.5bn, while Embedded rose 29% to $1.1bn and Gaming fell 40% to $773mn.
In my October 31 forecast, I said the number to watch was Client revenue, AMD’s PC chip business, after Intel’s PC warning dragged the stock lower. Client revenue rose 7% to $2.9bn. That supports the view that the October sell-off hit the smaller part of AMD’s business.
The 2027 Outlook Is the Real Story
For the fourth quarter, AMD guided to revenue of about $17bn, plus or minus 3%, which implies about 66% growth from a year earlier, with a non-GAAP gross margin near 55%. Gross margin is the share of revenue left after the direct cost of making chips.
On the earnings call, CEO Lisa Su said AMD expects revenue to grow more than 80% in 2027, with server CPU revenue roughly doubling and data center AI revenue growing significantly more than double. Data center should make up more than 80% of total revenue. Su said AMD has secured the wafers, substrates, advanced packaging and memory it needs, although demand still exceeds supply. In my view, 80% growth is a bold target for a company this size, and delivering it would put AMD among the fastest-growing large chipmakers.
The Weak Spots
Cash flow was thin. Operating cash flow of $1.2bn minus $648mn of equipment spending leaves roughly $554mn of free cash flow, the cash left after paying for operations and equipment. Inventory, chips built but not yet sold, rose to $11.5bn from $7.9bn at the end of 2025, a bet that Helios and new server chip demand will arrive on time. A $1.1bn non-cash charge tied to warrants issued to customers also lowered GAAP earnings. Warrants give holders the right to buy AMD shares, and their value rises when the stock rises.
What to Watch Next
The key signals are the Helios and MI450 shipment ramp, whether gross margin holds near 55% as AI chips make up more of sales, a recovery in free cash flow and any customer wins from Nvidia’s leadership change. AMD’s Q4 results are expected in early February 2027, although the company has not confirmed the date.
AMD Technical Analysis: $547.89 Fibonacci Support Is the Test
On the 4-hour chart, AMD trades at $549.78, down 3.65% in the current candle. The sharp rally from early November stalled at $593.56, where a falling trendline, a line connecting lower highs since October, turned buyers back. Price is now testing $547.89, the 23.6% Fibonacci retracement, a tool that measures how much of a rally gets given back.
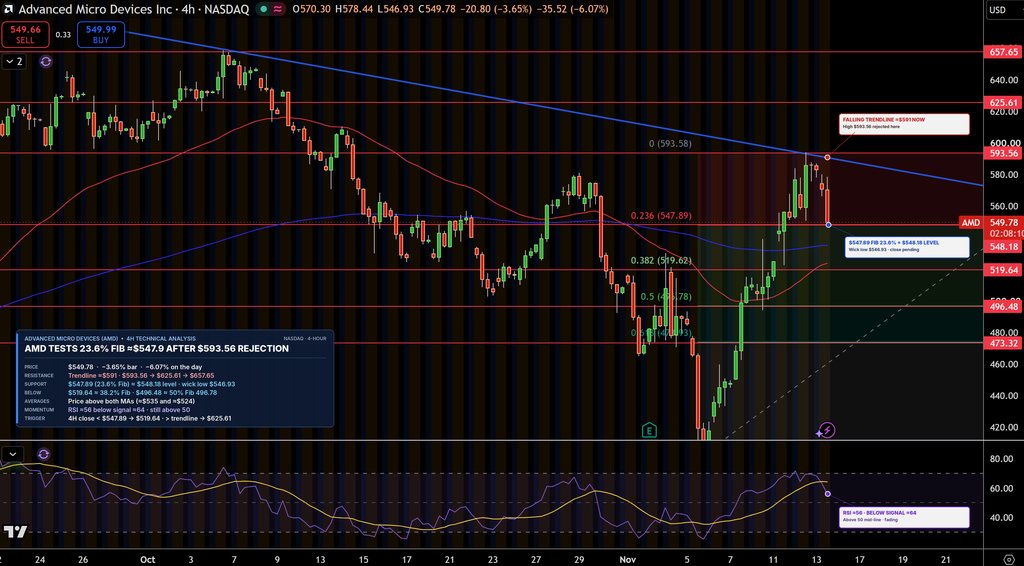
The RSI, a 0 to 100 momentum gauge, has turned lower and slipped below its signal line, though it remains above 50. Momentum is fading but has not turned bearish yet.
I lean cautiously bearish below $593.56. A 4-hour close below $547.89 targets $519.64, then $496.48, while a break above the trendline opens $625.61.
- Resistance: $593.56 | $625.61
- Support: $547.89 | $519.64 | $496.48
FAQs
Why did AMD stock rebound 45%?
AMD rallied on a Q3 beat, a 2027 outlook for more than 80% revenue growth and Nvidia’s surprise CEO change, which pushed investors toward Nvidia’s rivals.
What did AMD guide for 2027?
AMD expects revenue to grow more than 80% in 2027, with server CPU revenue roughly doubling and data center making up more than 80% of sales.
What is the key support for AMD stock?
The key support is $547.89, the 23.6% Fibonacci level. A 4-hour close below it would open $519.64, then $496.48.

Arslan Ali Butt
Lead Markets Analyst – Multi-Asset (FX, Commodities, Crypto)
Arslan Ali Butt serves as the Lead Commodities and Indices Analyst, bringing a wealth of expertise to the field. With an MBA in Behavioral Finance and active progress towards a Ph.D., Arslan possesses a deep understanding of market dynamics.
His professional journey includes a significant role as a senior analyst at a leading brokerage firm, complementing his extensive experience as a market analyst and day trader. Adept in educating others, Arslan has a commendable track record as an instructor and public speaker.
His incisive analyses, particularly within the realms of cryptocurrency and forex markets, are showcased across esteemed financial publications such as ForexCrunch, InsideBitcoins, and EconomyWatch, solidifying his reputation in the financial community.
