Key Points
-
Micron earned $28.2 billion in GAAP net income in its fiscal third quarter, which ended May 28.
-
Tesla’s GAAP net income for 2023, 2024, and 2025 combined totaled around $25.9 billion.
-
Micron’s CEO expects tight memory supply conditions to last past calendar 2027.
- These 10 stocks could mint the next wave of millionaires ›
At the start of 2026, Tesla (NASDAQ:TSLA) was worth more than five times as much as Micron Technology (NASDAQ:MU). That gap has nearly closed. Micron stock has almost quadrupled this year, but Tesla shares are off around 17% as of this writing.
That leaves the EV maker worth about $1.47 trillion, versus around $1.22 trillion for the memory specialist.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
The profit gap, though, goes the other way, and it’s not close. In its fiscal third quarter of 2026 (the quarter ended May 28, 2026), Micron’s net income was $28.2 billion under generally accepted accounting principles (GAAP). Tesla’s GAAP net income for 2023, 2024, and 2025 combined was around $25.9 billion.
Put another way, the less valuable business earned more in one quarter than the more valuable one did in three years. I don’t think the market keeps ranking them in that order much longer. My prediction is that Micron’s market value tops Tesla’s before 2028.
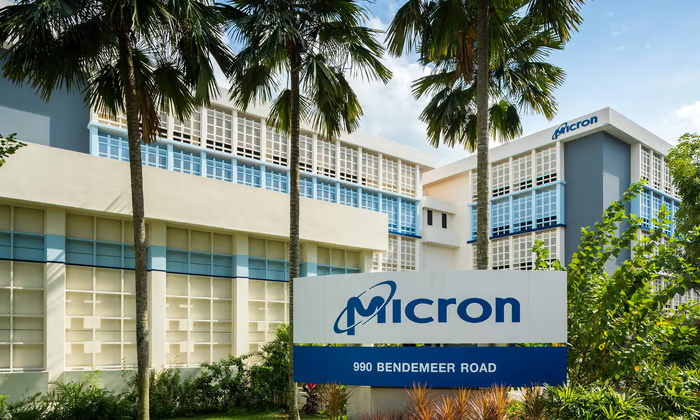
Image source: Micron.
Micron: the profits are already here
Showing how fast the memory boom has accelerated, Micron’s fiscal third-quarter net income more than doubled from $13.8 billion the quarter before, and it was around 15 times the $1.9 billion profit Micron made in the year-ago quarter. And during the first nine months of fiscal 2026, the business earned around $47.3 billion, almost nine times its profit over the same nine months a year earlier.
What’s more, the rise isn’t done. Management’s guidance for the fiscal fourth quarter, which ended in early September, calls for GAAP earnings of $30.73 per diluted share, plus or minus $1.00 — more profit than the third quarter delivered.
But the market isn’t paying much for these earnings. Micron’s stock price is just around 7 times the earnings per share analysts predict for its new fiscal year, fiscal 2027.
A price-to-earnings ratio that low arguably says investors see this year’s profits as a cyclical peak. And the caution has history behind it. The last memory downturn pushed Micron to a $5.8 billion loss in fiscal 2023.
Tesla: the price is built on what comes next
Tesla’s three-year total flatters it, too. Its 2023 GAAP net income of around $15.0 billion included a one-time non-cash tax benefit of about $5.9 billion. Without that, the three-year total falls to around $20 billion, which just extends Micron’s lead. And Tesla’s yearly profit has been declining since then, to $7.1 billion for 2024 and $3.8 billion for 2025.
The decline hasn’t reversed in 2026. Tesla’s second-quarter net income of $1.1 billion was 5% lower year over year, even with around $763 million of after-tax help from an unrealized gain on its SpaceX investment. Operating income was just 1.4% of revenue, down from 4.1% a year before.
In its latest four reported quarters, Tesla earned around $3.8 billion. Micron earned around 13 times as much profit in its own latest four.
Investors look to be paying for what Tesla might become — a business built on robotaxis and humanoid robots. At around $372, the stock trades at about 165 times the adjusted earnings per share analysts expect for 2027. But these future profits haven’t shown up in Tesla’s numbers yet.
Can Micron close a 20% gap?
If Tesla’s market value holds at around $1.47 trillion, Micron stock would have to hit about $1,300 per share, a little above its 52-week high of $1,255. Even then, Micron would still trade at just around 8 times the earnings per share analysts expect for fiscal 2027.
Or, if Micron’s shares stay put, Tesla stock would have to drop to about $309 — a price it traded under as recently as late July.
Either path gets easier if Micron’s profits hold up, and management thinks they can.
“We expect tight conditions to persist beyond calendar 2027 as a result of AI-driven demand across all segments coupled with structural supply constraints,” CEO Sanjay Mehrotra said on the company’s Juneearnings call
Additionally, management expects at least half of Micron’s revenue to eventually come under multi-year take-or-pay contracts, and the biggest of these deals have floor prices through their terms.
Still, a steep drop in memory prices would probably cut this call short. The fiscal fourth-quarter results, due after the close on Wednesday, Sept. 30, will show how much of the guided profit jump came through.
I think Micron’s reported profits push its market value above Tesla’s before 2028. Memory stocks can swing hard both ways, though, so the path there likely won’t be smooth.
Don’t miss this second chance at a potentially lucrative opportunity
Ever feel like you missed the boat in buying the most successful stocks? Then you’ll want to hear this.
On rare occasions, our expert team of analysts issues a “Double Down” stock recommendation for companies that they think are about to pop. If you’re worried you’ve already missed your chance to invest, now is the best time to buy before it’s too late. And the numbers speak for themselves:
- Nvidia: if you invested $1,000 when we doubled down in 2009, you’d have $585,136!*
- Apple: if you invested $1,000 when we doubled down in 2008, you’d have $65,062!*
- Netflix: if you invested $1,000 when we doubled down in 2004, you’d have $383,680!*
Right now, we’re issuing “Double Down” alerts for three incredible companies, available when you join Stock Advisor, and there may not be another chance like this anytime soon.
*Stock Advisor returns as of September 29, 2026.
Daniel Sparks has clients with positions in Tesla. The Motley Fool has positions in and recommends Micron Technology and Tesla. The Motley Fool has a disclosure policy.