Key Points
-
Auto industry customers spent around $8 billion on Nvidia’s AI systems for their own facilities in a recent 12-month stretch.
-
Nvidia’s automotive revenue was around 1% of its total sales in fiscal 2026.
-
Nvidia’s stock price is around 15 times its expected earnings per share for fiscal 2028.
- 10 stocks we like better than Advanced Micro Devices ›
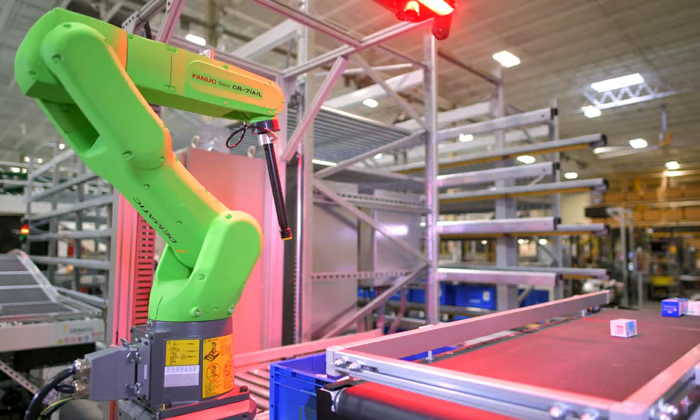
Physical AI is the name Nvidia (NASDAQ:NVDA) uses for artificial intelligence (AI) that works in the real world instead of onscreen. Picture the software that lets a warehouse robot lift a box, or a car steer itself through traffic. A chatbot just has to write an answer, but physical AI has to see what’s around it and then choose what to do.
Rivals want in. Advanced Micro Devices (NASDAQ:AMD) said on Sept. 28 that it had agreed to buy World Labs, a start-up that makes AI models of 3D spaces and tools for training robots, in an all-stock deal worth around $8.2 billion.
Missed AI’s “Act 1”? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
But for Nvidia, physical AI is still a small business in a huge firm. Its automotive revenue was around $2.35 billion over the 12 months through late January 2026 (Nvidia’s fiscal 2026), or about 1% of its total revenue of $215.9 billion. Even Nvidia’s broader physical AI number, around $6 billion in fiscal 2026, is below 3% of sales.
That doesn’t worry me. Actually, I think that’s one reason Nvidia is the simplest way for investors to own this trend.
Image source: Nvidia.
Nvidia already sells to robot and car makers
A physical AI system needs a few things. Its AI model has to be trained, which takes racks of powerful data center chips. It helps to practice in a simulated world before it touches a real one. And it needs a computer on board to make decisions in real time.
Nvidia sells into all three. For the on-board part, it has Jetson Thor, a computer made to go in robots, and its DRIVE Hyperion platform for self-driving cars. For training and simulation, it offers open AI models named Cosmos, plus the data center chips that run them.
“Amazon will also adopt our full physical AI stack, Omniverse, Cosmos, Isaac and Jetson to power its fleet of warehouse robots,” Colette Kress, Nvidia’s chief financial officer, said on the company’s fiscal second-quarter 2027earnings callin August.
What’s more, the training part might matter most today. Kress also noted that Nvidia’s sales of AI systems to auto industry customers for their own facilities hit around $8 billion in the past 12 months.
So, this spending shows up in Nvidia’s data center sales, not its car business.
Small, for now
Nvidia’s automotive revenue (the computers and software it sells automakers for self-driving and other in-car AI) climbed 39% in fiscal 2026. Still, growth slowed sharply as the year passed.
In the fiscal second quarter, automotive revenue was up 69% year over year. But that slid to 32% in the third quarter and just 6% in the fourth, when sales hit $604 million. In short, the in-car business settled at about $600 million a quarter in the last half of the year.
Nvidia no longer reports automotive separately, either. Since the start of fiscal 2027, it’s been rolled into a broader category called Edge Computing, along with products like PCs, game consoles, workstations, and robots.
Edge Computing revenue in the second quarter of Nvidia’s fiscal 2027 (the three months ending July 26, 2026) was $7.2 billion, up 27% year over year. Management credited the rise to strong sales of workstations and didn’t mention robots or cars. Data center revenue, in contrast, was $89.0 billion.
For now, physical AI hardly moves Nvidia’s numbers.
What about AMD?
AMD’s deal shows how seriously rivals take this market. AMD said World Labs should help it design future hardware around how AI workloads are changing, and it expects the deal to close by the end of 2026.
But for investors, the two stocks are valued very differently. AMD’s share price is about 41 times its expected 2027 earnings per share, using analysts’ consensus estimate. For Nvidia, at around $237 a share as I write this, the number is about 15 times expected earnings per share for fiscal 2028, which ends in January 2028.
At that price, I think Nvidia investors are paying mostly for a data center business that pulled in $89.0 billion last quarter alone. Its physical AI work arguably comes along at little added cost.
Granted, robots and self-driving cars might take years longer to pay off than the excitement suggests. And a slowdown in data center spending could hurt Nvidia much more than anything in its car business. After all, data centers brought in more than 90% of its revenue last quarter.
In the end, for investors who want a stake in physical AI without betting on which robot maker wins, I think Nvidia is the simplest answer. I’d buy the stock today mostly for its data center business. Robots and self-driving cars might add to it later, but I’m not banking on them yet.
Should you buy stock in Advanced Micro Devices right now?
Before you buy stock in Advanced Micro Devices, consider this:
The Motley Fool Stock Advisor analyst team just identified what they believe are the 10 best stocks for investors to buy now… and Advanced Micro Devices wasn’t one of them. The 10 stocks that made the cut could produce monster returns in the coming years.
Consider when Netflix made this list on December 17, 2004… if you invested $1,000 at the time of our recommendation, you’d have $385,972!* Or when Nvidia made this list on April 15, 2005… if you invested $1,000 at the time of our recommendation, you’d have $1,416,196!*
Now, it’s worth noting Stock Advisor’s total average return is 951% — a market-crushing outperformance compared to 214% for the S&P 500. Don’t miss the latest top 10 list, available with Stock Advisor, and join an investing community built by individual investors for individual investors.
*Stock Advisor returns as of October 9, 2026.
Daniel Sparks and his clients do not have positions in any of the stocks mentioned. The Motley Fool has positions in and recommends Advanced Micro Devices and Nvidia. The Motley Fool has a disclosure policy.