Key Points
Tim Cook had enormous shoes to fill when he took over the Apple (NASDAQ: AAPL) CEO role from Steve Jobs in 2011. Jobs was a visionary leader, and skeptics weren’t sure Cook was the right person to lead the consumer tech company into its next chapter. Fifteen years later, and the proof is in the pudding: Over Cook’s tenure, the tech giant experienced massive growth as its market cap ballooned from $350 billion to approximately $4.75 trillion.
John Ternus took over from Cook on Sept. 1, and as his time at the helm of Apple begins, he faces the same sort of questions. Long-term investors want to know: Can Ternus match Cook’s incredible run? How will the growth curve bend now?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
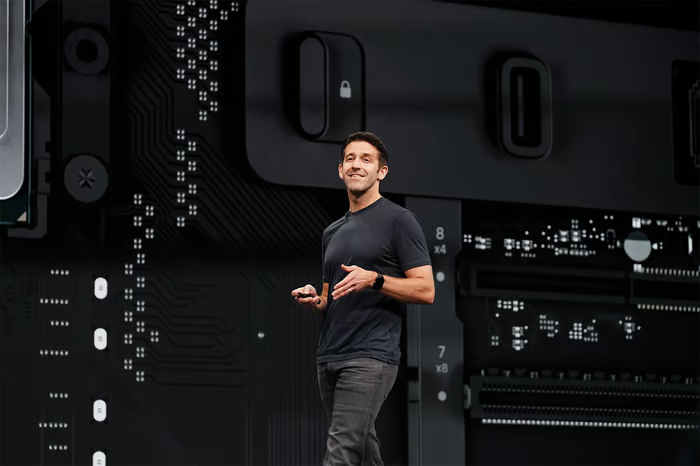
New Apple CEO John Ternus. Image source: Apple.
Apple is a dominant global player
Apple is in terrific shape, and that’s both good and bad news for Ternus. The company is a well-oiled machine, but expectations will remain elevated. In its fiscal third quarter, revenue grew 16% year over year. The growth was driven by iPhone sales that rose 21.7% and services revenue that rose 12%. Total revenue reached $109.4 billion.
Ternus is inheriting a business with immense recurring, high-margin, and diversified revenue. The downside is that the company’s latest revenue guidance was fairly muted — only 9% to 11% for the current quarter — as management anticipates intensifying supply constraints. This will mark Ternus’ first challenge, and investors will closely watch how he navigates this period.
There’s also the problem with China. Under Cook, Apple became extremely reliant on Chinese manufacturing. Ternus will need to work through geopolitical tensions, the need to geographically diversify its manufacturing footprint, and U.S. pressure to onshore more of its manufacturing. And there are plenty of questions about Apple’s long-term position in the artificial intelligence race.
Apple will be just fine
The good news is that Ternus is a 25-year Apple veteran and has had a front-row seat to all that the iPhone maker has endured over the last quarter-century. If the iPhone 18 Pro and iPhone Ultra (priced at more than $2,000) are successful, those will be not only morale wins but also economic ones.
Duplicating Cook’s run won’t be easy. I’d expect Ternus to usher in a new era of steady, but dialed-back growth over the next several years. A return to a focus on excellent design and innovation will be the real mark of success for the engineer-turned-executive.
Apple isn’t a young, scrappy tech start-up. It’s one of the largest companies in the world, and its cash-generating ability is astounding. It’s still worth investing in, but it’s not the growth stock it once was, and that’s OK.
Don’t miss this second chance at a potentially lucrative opportunity
Ever feel like you missed the boat in buying the most successful stocks? Then you’ll want to hear this.
On rare occasions, our expert team of analysts issues a “Double Down” stock recommendation for companies that they think are about to pop. If you’re worried you’ve already missed your chance to invest, now is the best time to buy before it’s too late. And the numbers speak for themselves:
- Nvidia: if you invested $1,000 when we doubled down in 2009, you’d have $621,091!*
- Apple: if you invested $1,000 when we doubled down in 2008, you’d have $63,501!*
- Netflix: if you invested $1,000 when we doubled down in 2004, you’d have $364,023!*
Right now, we’re issuing “Double Down” alerts for three incredible companies, available when you join Stock Advisor, and there may not be another chance like this anytime soon.
*Stock Advisor returns as of October 6, 2026.
Catie Hogan has positions in Apple. The Motley Fool has positions in and recommends Apple. The Motley Fool has a disclosure policy.