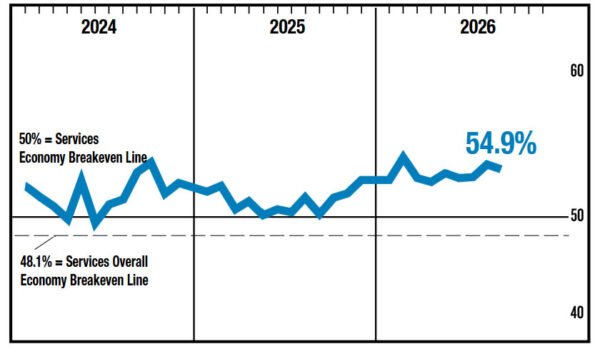
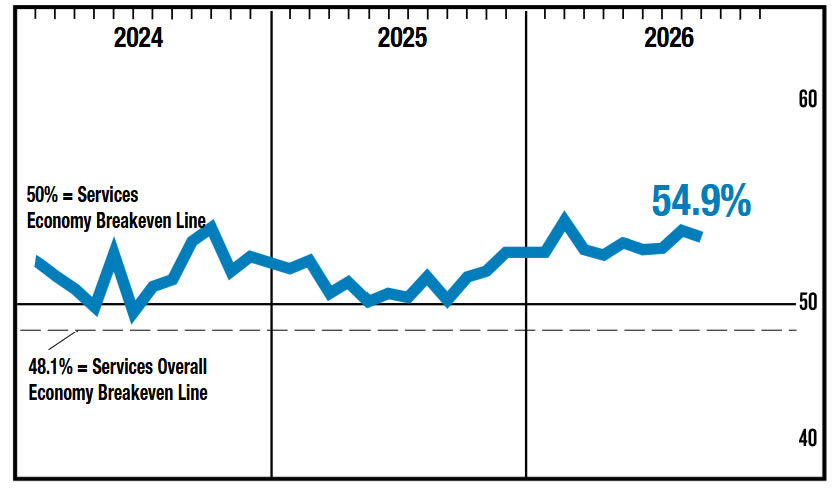
US ISM Services PMI eased from 55.4 to 54.9 in September, slightly below consensus of 55.3 but still signaling a solid expansion in the services sector. The moderation was led by softer activity and demand, with the Business Activity Index falling from 61.7 to 56.5 and New Orders easing from 60.9 to 59.8. Both nevertheless remained comfortably above 50, indicating slower rather than weak underlying momentum.
The internals were firmer on labor and considerably stronger on prices. Employment rebounded from 47.8 to 50.1, returning to expansion after three months of contraction, while Prices Paid accelerated from 72.6 to 74.0, its highest reading since July 2022. Supplier Deliveries rose from 51.3 to 53.2, indicating longer delivery times, while Backlog of Orders increased from 55.6 to 56.6. ISM said tariffs and fuel costs were the most frequently cited supply-chain concerns, with fuel costs mentioned roughly twice as often as any other single issue affecting performance.
The main weak spot was external demand, where New Export Orders plunged from 56.3 to 46.9, moving sharply back into contraction, while Imports slowed from 56.3 to 52.9. Overall, the report points to a services economy that is losing some momentum but remains firmly expansionary, with employment stabilizing and price pressures becoming more pronounced. The combination of still-solid domestic demand and higher input costs makes September’s report more mixed than the softer headline alone suggests.
Data Summary
| Indicator | Sep | Aug |
|---|---|---|
| ISM Services PMI | 54.9 | 55.4 |
| Business Activity | 56.5 | 61.7 |
| New Orders | 59.8 | 60.9 |
| Employment | 50.1 | 47.8 |
| Prices Paid | 74.0 | 72.6 |
| New Export Orders | 46.9 | 56.3 |
Headline ISM Services PMI was slightly below the 55.3 consensus.
Key Takeaways
- Services growth moderated: ISM Services PMI fell from 55.4 to 54.9, slightly missing the 55.3 consensus but remaining firmly in expansion.
- Activity cooled from strong levels: Business Activity dropped from 61.7 to 56.5, while New Orders eased from 60.9 to 59.8.
- Employment improved: the Employment Index rose from 47.8 to 50.1, returning to expansion after three months below 50.
- Price pressure intensified: Prices Paid climbed from 72.6 to 74.0, its highest reading since July 2022.
- Supply conditions tightened somewhat: Supplier Deliveries increased from 51.3 to 53.2, while Backlog of Orders rose from 55.6 to 56.6.
- Fuel and tariffs remained major cost pressures: ISM said fuel costs were cited roughly twice as often as any other single issue affecting performance.
- External demand weakened sharply: New Export Orders plunged from 56.3 to 46.9, moving from expansion into contraction.
- Overall, the report shows slower but still-solid services growth alongside recovering employment and stronger inflation pressure, making the internals firmer than the softer headline alone suggests.