Shopify’s NASDAQ: SHOP stock sold off following its Q3 earnings release on fears that may be overblown given the company’s fundamental strength. Ultimately, it comes down to valuation: the approximately 80x current-year consensus earnings multiple it traded at before the release was high, pricing in perfection and leaving little room for weakness. The roughly 1% miss in gross merchandise value (GMV) was relatively minor, while other financial metrics remained strong.
Shopify Sustains Momentum, Widens Operating Margins
Shopify Today
As of 11/3/2026 04:00 PM Eastern
- 52-Week Range
- $94.00
▼
$180.88
- P/E Ratio
- 96.33
- Price Target
- $178.49
Shopify had an outstanding quarter, sustaining a 31.6% revenue growth rate and roughly matching analysts’ expectations. While GMV fell slightly short, adjusted earnings exceeded estimates. Within this, the higher-margin Subscription Solutions business grew by 19.5% while Merchant Solutions grew a stronger 35.5%. Monthly recurring revenue, another key detail, grew more than 19% and provides long-term visibility.
Margin news is the real strength. While gross margins compressed, the decline reflected a shift toward Merchant Solutions, along with higher AI and hosting costs. Operating profit grew 65.5%, while free cash flow increased about 61%. Free cash flow is significant because the company is profitable, has a fortress-like balance sheet, and is reducing its share count through buybacks. Buybacks amounted to more than half a billion in the quarter, reducing the count by about 1.1% year over year.
Guidance is another factor suggesting the post-release sell-off is an overreaction. The company guided Q4 revenue growth to the low-30s, above the 29% consensus expected by analysts. That outlook suggests continued momentum heading into the holiday shopping season, although actual results could differ from expectations. As it stands, analysts forecast growth to slow into the upper-20% range in 2027.
Reasons to believe the company will outperform are the strong guide going into peak holiday shopping, enterprise wins, and ecosystem expansion. Ecosystem expansion includes add-ons and tools, along with partnerships such as the one with Condé Nast; it can support customer conversion and expand Shopify’s reach. Enterprise wins include names such as Mattel NASDAQ: MAT and Hasbro NASDAQ: HAS, which use Shopify for major e-commerce storefronts.
Analyst Trends Are Strong, But Headwinds May Emerge
Analyst data shows strong conviction in Shopify’s investment thesis: MarketBeat tracks 49 analysts, and the consensus is Moderate Buy. The problem is the Q3 miss and its potential impact on sentiment, which could increase caution. Any subsequent price target cuts could create a headwind for price action. Consensus as of early November is near $178, aligning with the existing highs and suggesting potential upside.
Institutions Will Signal the Bottom in Shopify Stock
Institutions are among the risks in Q4. The group owns about 70% of the shares and could influence where the stock finds support. While they bought in 2026, activity is light and may remain so until a bullish catalyst emerges. The question is whether the recent decline is enough to ramp activity, or whether they wait for lower prices before stepping in to provide support.
Shopify MarketRank™ Stock Analysis
4.16030022785 of 5 stars
- Overall MarketRank™
- 83rd Percentile
- Analyst Rating
- Moderate Buy
- Upside/Downside
- 24.8% Upside
- Short Interest Level
- Healthy
- Dividend Strength
- N/A
- News Sentiment
- 0.51
- Insider Trading
- N/A
- Proj. Earnings Growth
- 26.03%
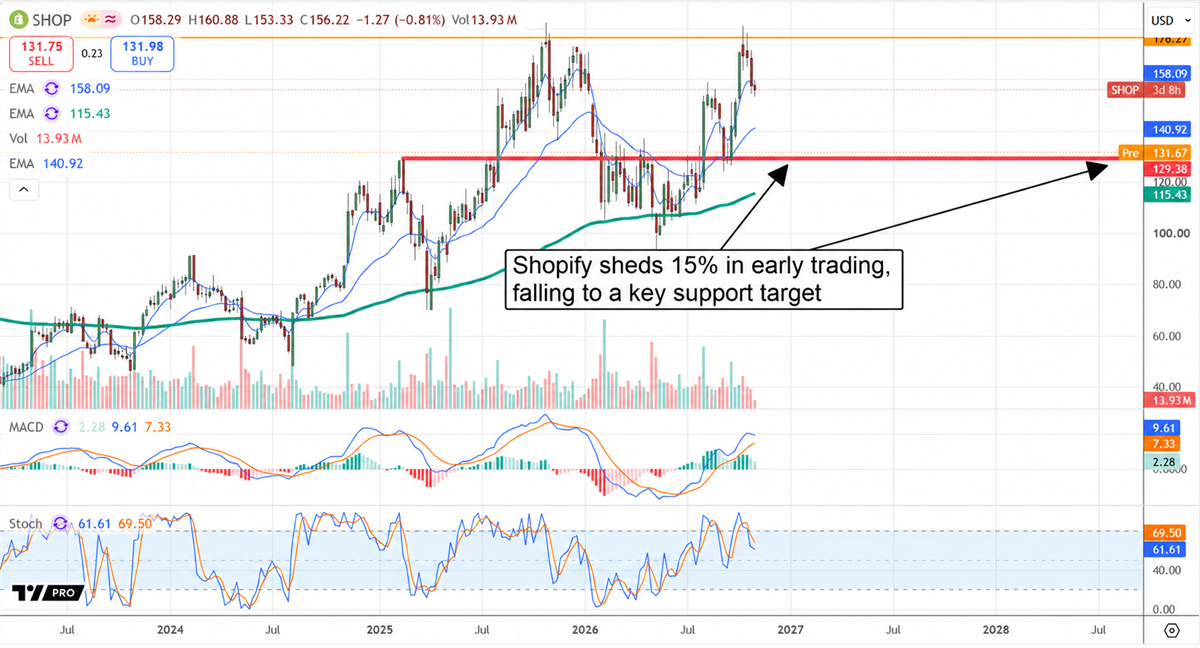
Potential support levels are near $130, $115, and $100, with $100 a possible lower target should the higher levels break. $130 aligns with a technical pivot point and may be a strong level; the risk is that price falls below it and the market sells off. In this scenario, Shopify could fall below $100 before rebounding, although a rebound is not guaranteed. The valuation may be justified given the quality of its cash flow, but it is still high and a hurdle for cautious investors.
Catalysts include Shopify’s shift to become the checkout layer for eCommerce. Its architecture allows traffic from different shopping channels to reach Shopify’s checkout infrastructure. More importantly, orders originating from AI channels grew 3.3x year over year, while AI-referred shoppers converted 64% more often than organic-search visitors. Shopify is also integrating with AI interfaces such as Meta Platforms’ NASDAQ: META Muse. Expanding merchant services, scaling the ecosystem, and further international expansion also present growth opportunities.
Shopify’s platform controls, which can present challenges for businesses in some highly regulated markets, are another risk. Certain restrictions may limit how these businesses use Shopify’s services, potentially limiting the total addressable market and long-term growth potential.
Before you consider Shopify, you’ll want to hear this.
MarketBeat keeps track of Wall Street’s top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on… and Shopify wasn’t on the list.
While Shopify currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
AI spending is reshaping the market, and the opportunity extends far beyond the biggest chipmakers. Discover 10 stocks set to benefit from powerful trends in AI infrastructure, cloud computing, energy, capital returns, and consumer growth this fall.
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.