China’s new 20% tax on offshore trust income has turned what used to be quiet wealth planning into a race against the clock, with founders, family offices, and private-banking clients scrambling to raise cash. Forced selling, share-backed loans, and shifting residency plans are colliding to create pockets of stress and potential openings. This article focuses on three Hong Kong and Singapore listed wealth platforms that appear most exposed to that storm.
The three Hong Kong and Singapore listed stocks below are just a starter pack. The full screen surfaced 52 more financial groups with equally detailed narratives that are not covered here. To move from a short watchlist to your own filtered target list, head straight into the Hong Kong and Singapore-listed institutional trust and private-banking service providers screener to identify, analyze, and focus on the highest conviction ideas.
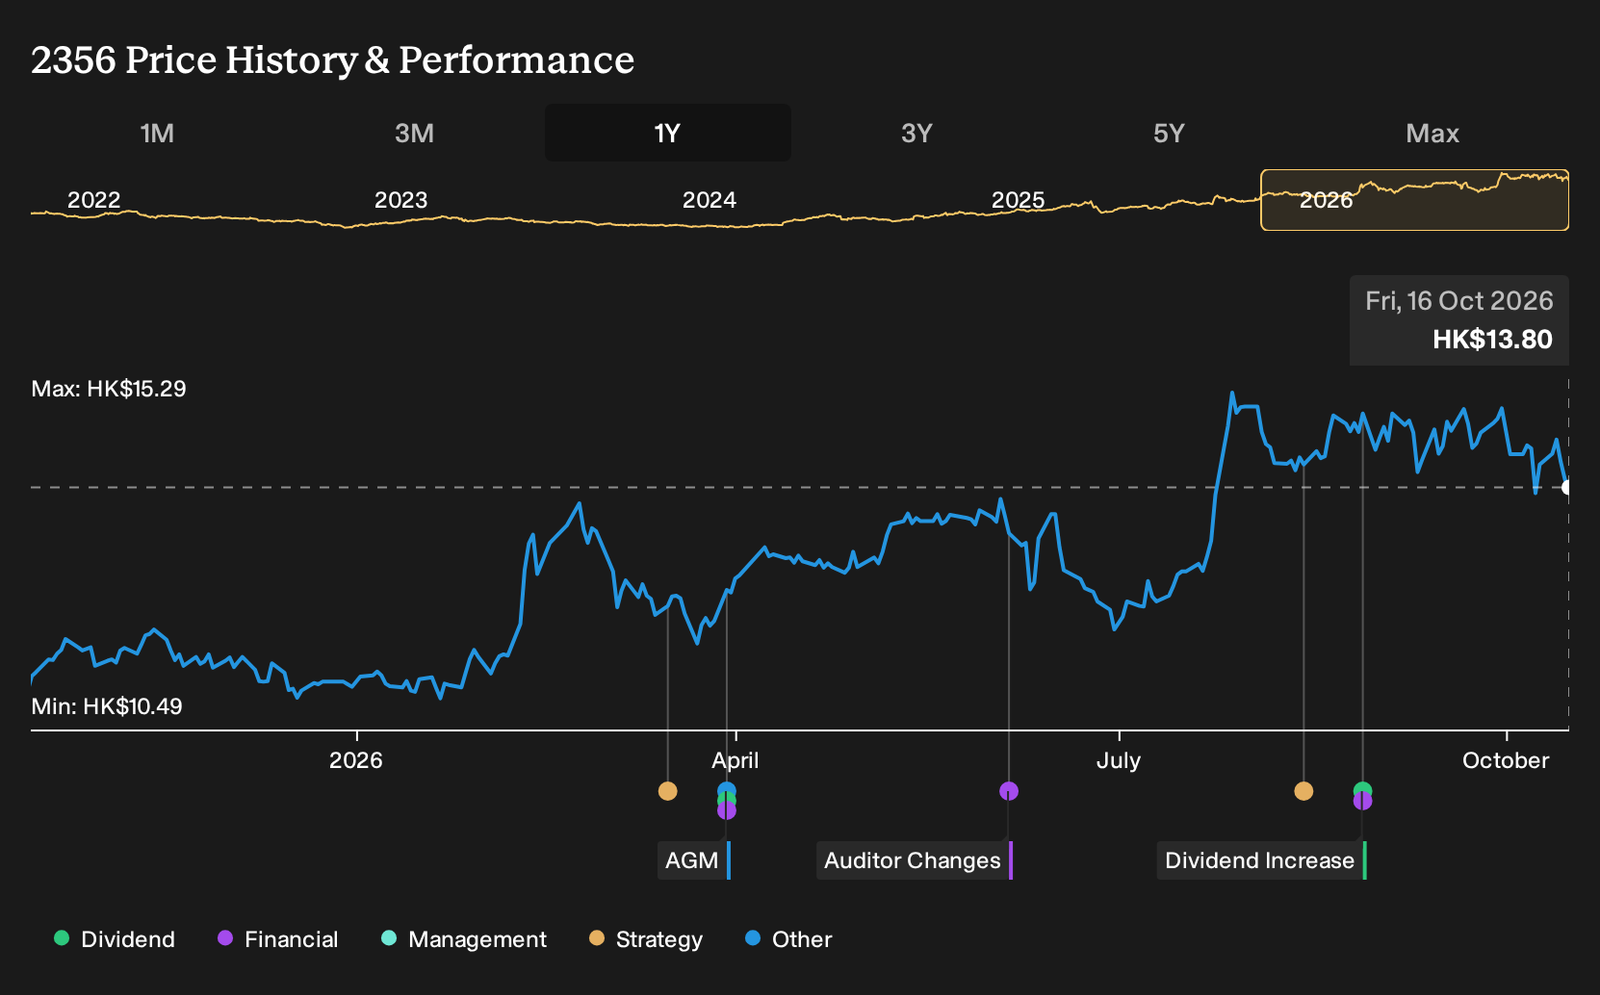
Dah Sing Banking Group (SEHK:2356)
Dah Sing Banking Group is a Hong Kong headquartered banking group with operations across Hong Kong, Macau and mainland China that fits the screener through its full service retail, corporate and wealth focused offering for regional clients using Hong Kong as a financial hub. Revenue is anchored in Personal Banking at about HK$3.7b, with HK$2.2b from Treasury and Global Markets and HK$517 million from Mainland China and Macau Banking. The stock’s market value is around HK$19.4b.
For investors interested in Hong Kong and China linked wealth platforms, Dah Sing Banking Group offers a mid sized regional bank that already serves personal, corporate and cross border clients who rely on Hong Kong for banking and asset administration. The key consideration is how one unresolved pressure shapes fee rich wealth and trust related income versus credit risk and funding costs.
That pressure point is exactly why the 3 key rewards and 3 important warning signs is important, so you can see where Dah Sing Banking Group’s fee engine and credit exposure may be decoupling.

Dah Sing Financial Holdings (SEHK:440)
Dah Sing Financial Holdings is a Hong Kong based financial group in the institutional trust and private banking screener because its banks and insurers serve cross border wealth, pension, and investment needs. Revenue leans on Personal Banking at about HK$3.7b and Treasury and Global Markets at roughly HK$2.2b, with Insurance and Investment Operations at about HK$288 million. The group’s market value is around HK$13.8b.
Dah Sing Financial Holdings links everyday retail banking with insurance and investment products that matter for trust, custody, and private banking clients who want Hong Kong, Macau, and Mainland China coverage through a single group. The interest for you is how that mix of fee income and balance sheet risk responds if a single key assumption breaks.
If that core assumption is starting to look fragile for you, jump into the 3 key rewards and 3 important warning signs to see what might be quietly accelerating or stalling beneath the surface.

Bank of East Asia (SEHK:23)
Bank of East Asia is a Hong Kong headquartered lender in this trust and private banking screener because it runs retail, wealth management and private banking operations across Hong Kong, Mainland China and nearby markets. Revenue is driven by Hong Kong personal banking at about HK$7.3b, with wealth management at HK$1.5b and Mainland China at HK$2.7b, on a roughly HK$48.7b market value.
For investors focused on institutional trust and private banking themes, Bank of East Asia offers a large Hong Kong platform with meaningful wealth management, private banking and cross border services that sit on top of a sizeable personal banking franchise. The interest is in what happens when pressure on credit quality and returns meets high expectations baked into a richer P/E multiple.
When those expectations feel stretched, head to the 2 key rewards and 3 important warning signs to see how Bank of East Asia’s valuation, credit risk and wealth momentum may be diverging.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Watch where early momentum forms, where potential breakouts build, and which stories stay under the radar for now. Do not delay, get in early.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Bank of East Asia might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com