The Morning Bull – US Market Morning Update Tuesday, Oct, 13 2026
US stocks are set for a cautious positive open, with sentiment pinned to one thing: inflation expectations in the US consumer survey just pushed higher, keeping the rate debate very much alive.
The University of Michigan index printed a weak 46.3 in early October, while year-ahead inflation expectations hit 4.7%, a five-month high. That combination points to strained households and worries that price pressures remain sticky into this week’s CPI and PPI data.
When consumers expect nearly 5% inflation, bond investors often demand more yield to protect real returns. Higher yields lift borrowing costs for companies and households, which can pressure profit margins and reduce appetite for longer-duration growth stories.
The open now hinges on a simple question: do this week’s inflation releases confirm those elevated expectations or undercut them? The answer is likely to influence how far investors are willing to push this early bid in US equities.
Stocks to Watch Before the Opening Bell
Walt Disney (DIS)
Character.ai has entered voluntary Chapter 11, with Walt Disney lined up as stalking horse bidder for a non-exclusive perpetual license to some of its intellectual property. Disney is also set to provide transition services. This offers an early look at how Disney might source new AI and personalization technology. Watch for deal terms and closing timing into late November or early December 2026.
Meta Platforms (META)
Meta Platforms has unveiled Muse Wonder, described as its most advanced AI model so far and aimed at business customers. Management also states that it plans to keep investing heavily in AI research and infrastructure. In addition, Meta bought a batch of VR patents from Sony, which could reshape its metaverse toolkit even as the focus shifts more toward artificial intelligence.
PTC (PTC)
PTC is under the microscope after Halper Sadeh LLC opened an investigation into its agreed sale to Schneider Electric for US$205.00 per share in cash. The law firm is reviewing whether shareholders are receiving a fair deal and whether any fiduciary duties were breached. Investors in PTC will be watching for potential calls for higher consideration or additional disclosures around the merger process.
Top Movers
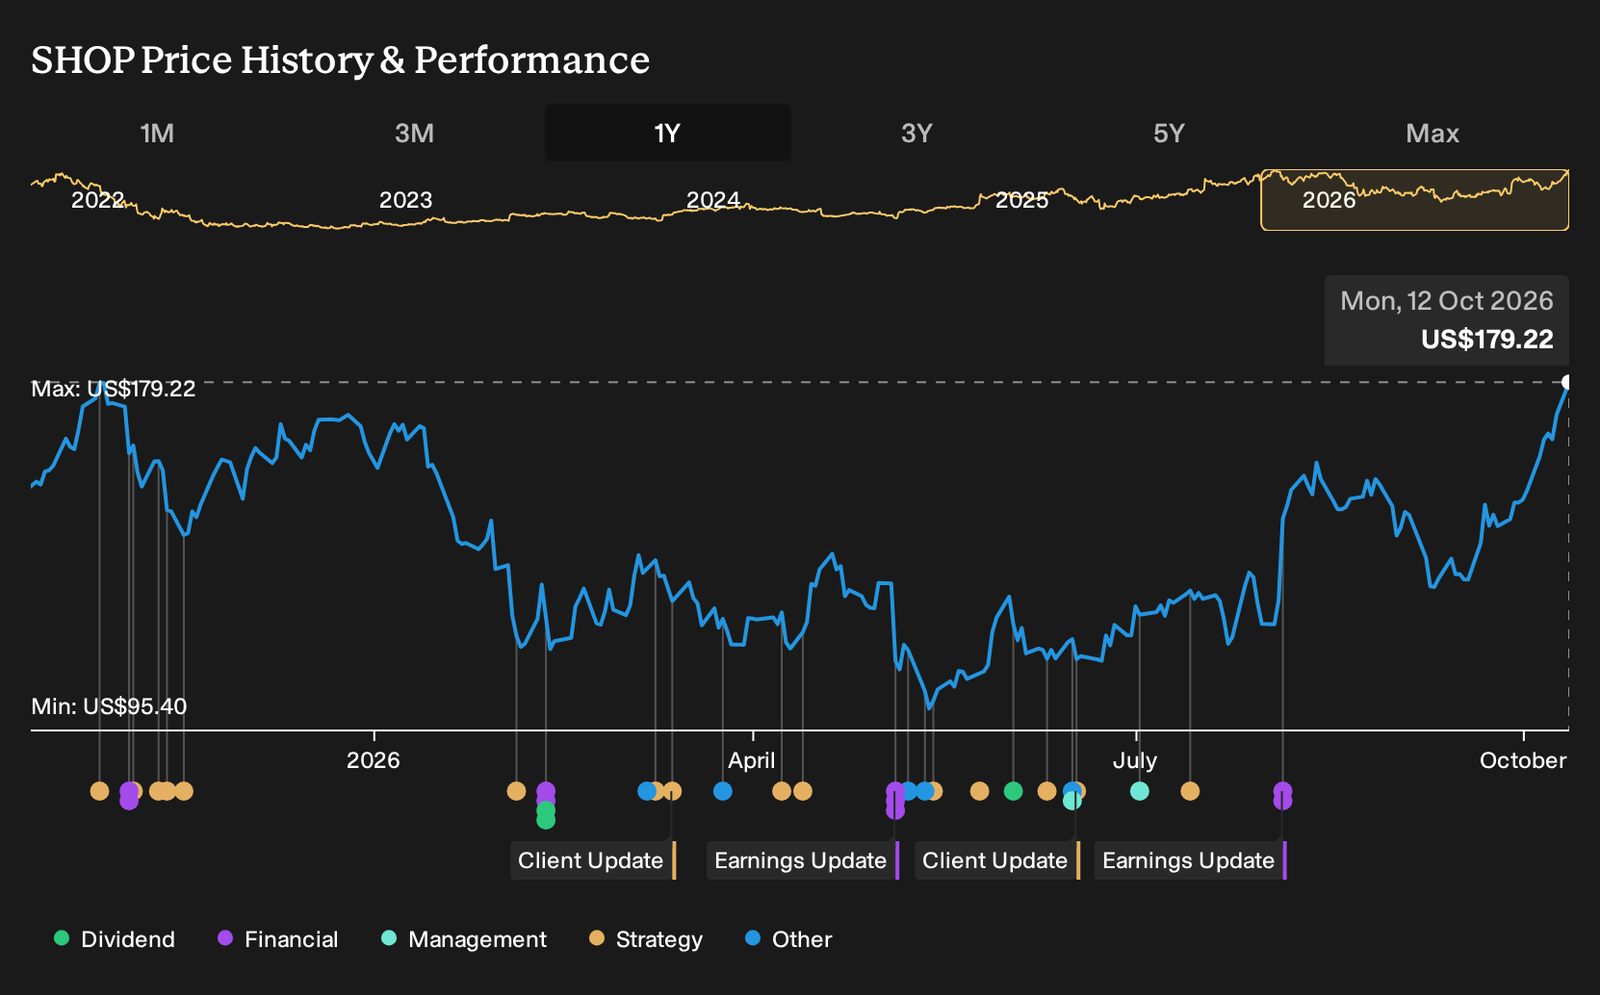
- Shopify (SHOP) jumped 4.90% after multiple analysts lifted price targets and highlighted strength in AI driven agentic commerce.
- Medtronic (MDT) gained 3.90% as investors reacted to updated analyst research and prior guidance for higher FY27 revenue and EPS.
- Vylor (VYLR) advanced 3.75% following fresh analyst coverage and recent inclusion in major equity indices after its spinoff.
Top Losers
- Ciena (CIEN) fell 9.95% after investors reacted to the appointment of a new Chief People Officer.
- Lumentum Holdings (LITE) declined 9.78% as AI infrastructure funding concerns hit optical networking stocks, despite commentary describing demand as strong over the longer term.
- Coherent (COHR) dropped 7.87% during a broader selloff in optical networking shares tied to concerns about the sustainability of AI-related spending.

On The Radar
US inflation data and a fresh wave of bank and health care earnings take center stage over the next few sessions, with Fed speakers adding another layer to the rates conversation.
- US CPI and Core CPI, Wed 14 Oct. A monthly CPI forecast of 0.5% with core at 0.2% and headline year on year at 3.7% puts every basis point in focus for Treasury yields and rate sensitive growth stocks.
- US PPI and Core PPI, Thu 15 Oct. Producer prices expected at 0.5% on the headline and 0.3% on core will feed directly into views on corporate cost pressure and pricing power across Industrials and Consumer sectors.
- US Retail Sales, Thu 15 Oct. Headline spending is projected to slow to 0.3% after 1.2%, with the control group seen at 0.3%. A softer print would point to more cautious consumers for retailers and discretionary names.
- US Industrial Production, Fri 16 Oct. Output is forecast to move from flat to a 0.4% gain, and any miss against that bar would weigh on sentiment in cyclicals tied to manufacturing and freight.
- JPMorgan Chase (JPM), Bank of America (BAC), Citigroup (C), Goldman Sachs (GS), Morgan Stanley (MS), Tue 13 to Wed 14 Oct. Q3 results put net interest income, trading revenue and credit costs under the microscope and will heavily influence how investors treat the wider US financials sector this week.
Sector & Industry Watch
Tech: AI buildout meets rate anxiety
Tech has slipped over the past week after a very strong year to date run, even as Microsoft, Salesforce and others keep rolling out new AI chips, cloud tools and data center projects. Higher US inflation expectations are pushing up rate worries, which often hits sectors where a lot of the pay off sits years into the future.
If a big chunk of your portfolio tracks Tech, swings now hinge on both AI spending headlines and bond yields. Wednesday’s US CPI report is the key catalyst because a firmer reading would support higher yields and keep pressure on richly valued software and hardware stocks.
Semiconductors: Hot year, cooler short term mood
Semiconductors show a clear 7 day pullback after very strong year to date and 1 year returns, as traders react to talk about tight financing for AI projects and fresh competition in memory. News around Nvidia, Micron, Sandisk and in house AI chips from Microsoft and Intel keeps attention on whether data center demand can comfortably support recent gains.
For chip heavy portfolios, that means daily moves are closely tied to every update on AI capex plans and funding costs rather than just tech hype. The sector’s most important near term macro trigger is also Wednesday’s US CPI print, since stickier inflation would keep borrowing costs higher for the huge factory and data center builds these companies sell into.
Energy: Fuel tightness still helping producers
Energy and the Oil and Gas group both post firm 7 day gains on top of strong year to date performance, helped by reports that US refiners enjoyed very strong Q3 returns as fuel markets stayed tight. Stories around refiners such as Valero, Marathon Petroleum and Phillips 66, plus tanker operators benefiting from disrupted trade routes, show how much earnings in this sector depend on diesel and gasoline margins as well as crude prices.
If you hold Energy ETFs or producer stocks, your returns are tied to whether fuel spreads and shipping rates remain supportive for profits. The clearest near term check is this week’s US crude and gasoline inventory data, which will signal whether supply is catching up with demand or staying strained into the next quarter.
Real Estate: Rate sensitive bounce with mixed signals
Real Estate has delivered a positive 7 day move after a weaker 30 day patch, which fits a sector that reacts quickly to changes in bond yields and mortgage costs. Data center and tower landlords such as Equinix and Crown Castle sit alongside more traditional office and housing exposure, so income streams can look steady even while higher rates weigh on property values and refinancing.
If you own REITs or property heavy funds, the key real world link is simple. Higher long term yields raise borrowing costs and influence what buyers can pay for buildings. This week’s US existing home sales report and the MBA 30 year mortgage rate reading will show whether higher financing costs are still cooling housing activity or starting to level off.
Consumer Staples: Everyday spending holds up better than mood
Consumer Staples have logged a solid 7 day gain and are in positive territory year to date, even as the Michigan survey shows sentiment near a five month low. Legal disputes around Kroger and Albertsons, plus steady updates from Walmart, Costco and Kraft Heinz, suggest households may hunt for bargains yet still prioritise groceries and household basics over big ticket items.
If you use Staples as the steadier part of your portfolio, focus on whether shoppers keep filling baskets rather than what they tell surveys. Thursday’s US Retail Sales control group, which strips out more volatile items, is the main data point to watch because it gives a cleaner read on core goods spending that underpins this sector.
Find Tomorrow’s Top Performers
With inflation expectations in the Michigan survey pushing to 4.7%, income focused investors who want sturdier cash flows may start with this list of 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com