Key Points
-
$1.4 billion in cost savings is what Lucid’s “Value Creation Team” is targeting in 2026.
-
Lucid’s midsize platform and first launch vehicle, Cosmos, are delayed, but their importance has never been greater.
-
Lucid’s Saudi Arabia factory remains an “X-factor” as it comes with large-scale stable government orders, but needs to reach industrialization sooner rather than later.
- These 10 stocks could mint the next wave of millionaires ›
There was an initial shock to Lucid‘s (NASDAQ: LCID) stock price when it was announced that the company was working with restructuring consultant AlixPartners. Lucid and AlixPartners were both quick to dispel rumors of a potential bankruptcy, and after their work together concluded, AlixPartners concluded it was not recommending bankruptcy.
For investors willing to accept the risk that Lucid may in fact never turn its business around and may always be plagued by struggling gross profits, heavy cash burn, and consistent delays/recalls, its stock price could definitely pop if it can prove tangible progress in its turnaround. Here are four projects for investors to keep an eye on as Lucid tries to become the latest turnaround success story while rewarding investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
Four must-win projects
For Lucid to start giving investors optimism, it first needs to execute its cash-saving plan, especially given that the company’s cash burn remains elevated and the electric vehicle (EV) maker has failed to protect shareholders from significant dilution amid capital raises. More specifically, Lucid has identified $1.4 billion in cash reductions for 2026 alone. That will be driven by roughly $600 to $800 million in inventory optimization, roughly $500 million in reduced capital expenditures, and another roughly $200 million in operating expense savings.
Hand in hand with Lucid conserving cash and lowering costs is the EV maker’s upcoming midsize platform. Part of Lucid’s “operational reset” and $1.4 billion in savings comes from a decision to delay the production of this platform. The first vehicle to be launched on the new and more efficient midsize platform will be the Cosmos SUV, which is now slated to make its debut during the second half of 2027.
Though the Cosmos is delayed, investors shouldn’t put the company’s midsize platform on the back burner, as its importance remains significant. Lucid is targeting its Cosmos SUV to check in with a price under $50,000, aiming to expand Lucid’s total addressable market by roughly 10 times.
But the midsize platform is more important than only launching the Cosmos, and it’s projected to underpin the adventure-oriented Earth model, a third yet-to-be-named model, and a purpose-built Lunar robotaxi concept. The midsize platform is designed for a smaller 69 kWh battery pack to achieve roughly 300 miles of range. Using the company’s new compact Atlas drive unit, which reduces parts count by 30% and costs by 37%, should finally help Lucid improve its gross margin — Rivian has far outpaced Lucid in consistently improving gross margins.
Driverless tech can be lucrative
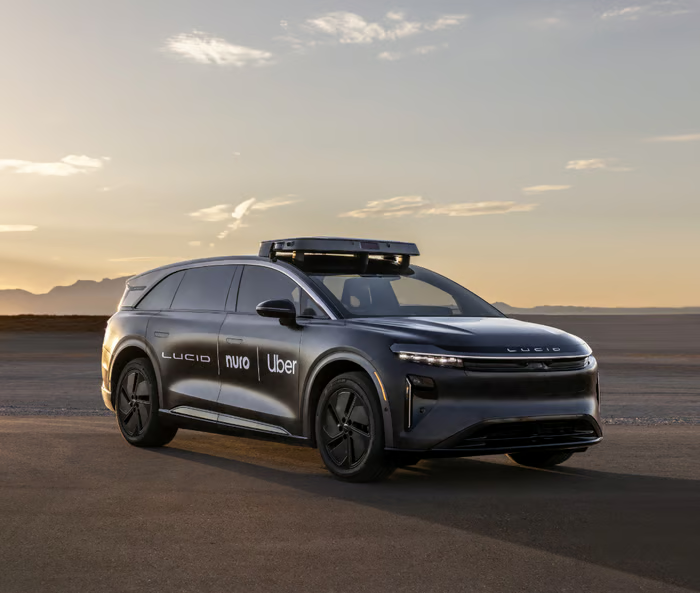
Another must-win for Lucid will be its ability to develop its robotaxi and other driver-assistance features that can be monetized. Remember that Lucid, along with Uber Technologies and Nuro, announced plans to bring all three companies together to design and produce a robotaxi based on the Lucid Gravity SUV, upfitted with Nuro’s L4 Nuro Driver system. Many investors also overlooked Lucid’s more recent partnership with European ride-hailing juggernaut Bolt.
Image source: Lucid.
The deal with Bolt calls for Lucid to supply at least 25,000 autonomous vehicles using its upcoming, and currently delayed, midsize EV platform. Lastly, at Lucid’s most recent investor day, it unveiled a purpose-built, two-seat dedicated robotaxi concept named Lunar. The steering wheel and pedals have been removed, but keep in mind that Lucid faces the same cloudy regulatory approval process that Tesla is navigating amid its Cybercab development.
The fourth project Lucid needs to complete is its curious factory in Saudi Arabia. The factory is transitioning from construction to industrialization with manufacturing systems that include stamping, paint, body, and, of course, final assembly, which are being prepared for production test runs.
What it all means
Lucid’s factory in Saudi Arabia is often an afterthought in investors’ theses, but it could play a pivotal role in the young EV maker finally finding some business stability, as it has secured large-scale, multiyear government fleet purchase orders. The overseas factory is also backed up by roughly $3.4 billion in financing and incentives over the next 15 years. It can become an instrumental player in Saudi Arabia’s Vision 2030, which aims to build a local EV ecosystem to serve theglobal market— there’s opportunity here, more than investors give it credit for.
Lucid has a lot on its plate, the odds seem stacked against it, and it lacks the progress to show investors, in both shareholder dilution and gross margins, that its close rival Rivian has consistently demonstrated. Lucid has to execute on these four projects because it has to quickly prove to investors that it has long-term potential, and time is running out.
Where to invest $1,000 right now
When our analyst team has a stock tip, it can pay to listen. After all, Stock Advisor’s total average return is 936%* — a market-crushing outperformance compared to 211% for the S&P 500.
They just revealed what they believe are the 10 best stocks for investors to buy right now, available when you join Stock Advisor.
*Stock Advisor returns as of October 3, 2026.
Daniel Miller has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Tesla. The Motley Fool recommends Uber Technologies. The Motley Fool has a disclosure policy.