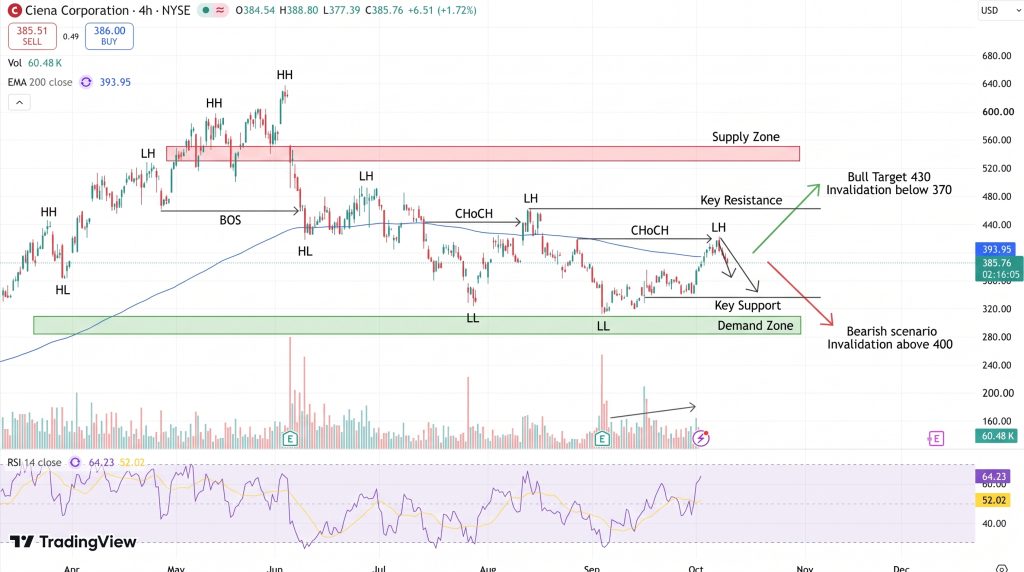
Ciena Corporation (NYSE: CIEN) is trading at $379.14 on October 2, 2026, showing more than 7.8 percent gain on the day. Its trading volume is also showing solid growth and its market capitalization stood near $50 to 54 billion at that time. Since we all know, Ciena Corporation designs and sells optical networking systems as well as interconnect products, automation software, and related that help move huge amounts of data through networks and AI data centers. This enables Ciena to benefit from growing global data and AI demand.
Record Third-Quarter Results Show Strong Demand
However, the proof of Ciena’s growth can also be seen in its third quarter of fiscal 2026 results, which showed that Ciena made revenue of $1.67 billion, which was a 37% increase from $1.22 billion in the same quarter last year.
Not only this, the company’s adjusted earnings per share hit a record of $2.11, increased 215 percent from $0.67 a year earlier. In the meantime, the GAAP diluted earnings per share also rose, reaching $1.83 and in the previous year it was around $0.35. Adjusted gross margin also improved to around 46.4%, while adjusted operating margin hit the record 22.5%. This was more than double last year’s figure and above the company’s guidance.
The story is not ending here, the Cloud provider customers made up 53% of Ciena’s total revenue during the quarter that was up 82% from the same period last year. It should also be noted that the two major customers alone accounted for about 41.7 percent of total sales and most of the growth came from networking platforms and optical systems. So we can say the company’s main earning source is networking platforms and optical systems.
On the other side, Ciena’s backlog also showed a huge jump by $800 million from the previous quarter, reaching $8.5 billion by the end of the quarter. Looking at the all good things, the company expects to finish fiscal 2026 with more than $10 billion in backlog and with most orders set for delivery in 2027 or later.
Therefore, Ciena’s strong Q3 results, including strong revenue report, a record adjusted EPS, and huge backlog, helped the stock and also improve the analyst point of view about the stock of company.
Guidance Raised for 2026 and Longer-Term Targets Set
Since everything is going well, Ciena raised its full year fiscal 2026 revenue guidance to $6.42 billion. This means Ciena could grow by around 35 percent as compared to the last year. For the fourth quarter, Ciena expects to make about $1.75 billion in revenue that is huge. Gross margin should be around 45%, and operating margin around 20%.
Looking further ahead, Ciena shared its longer term financial targets for fiscal 2029 at its Investor Forum on September 16, 2026 in which it is revealed that the company is targeting around $14 billion in revenue, which would mean roughly 30 percent annual growth from 2026 levels. It also expects adjusted gross margin to reach around 50 percent, adjusted operating margin to be between 32% and 35%, and free cash flow margin to be around 20%.
AI Demand, Subsea Wins, and Product Momentum
Lets discuss the major factor behind the company fast growth and the first factor comes in the mind is the rapid expansion of AI data centers. Since these data centers need fast connections that can handle huge amounts of data so Ciena company is benefiting from this demand through products like coherent optical pluggables, RLS Hyper Rail, and other data-center networking solutions. This is a huge win for Ciena.
Not only this but the company has also won several major subsea cable projects. Ciena was selected by the Africa Coast to Europe (ACE) consortium to upgrade a roughly 17,000 kilometer route connecting Western Europe, West Africa, and South Africa. The upgrade is expected to provide more than 30 terabits per second of capacity using Ciena’s technology.
Ciena is also seeing strong demand in metro networks. For example, its work with CtrlS Datacenters in India involves connecting multiple facilities with capacity of up to 100 Tb/s, highlighting the broader demand for high-capacity optical networking.
Analyst Views and Valuation Context
Looking at its so many positive things, Wall Street analysts are positive on Ciena, with many rating the stock as a Buy.

Arslan Ali Butt
Lead Markets Analyst – Multi-Asset (FX, Commodities, Crypto)
Arslan Ali Butt serves as the Lead Commodities and Indices Analyst, bringing a wealth of expertise to the field. With an MBA in Behavioral Finance and active progress towards a Ph.D., Arslan possesses a deep understanding of market dynamics.
His professional journey includes a significant role as a senior analyst at a leading brokerage firm, complementing his extensive experience as a market analyst and day trader. Adept in educating others, Arslan has a commendable track record as an instructor and public speaker.
His incisive analyses, particularly within the realms of cryptocurrency and forex markets, are showcased across esteemed financial publications such as ForexCrunch, InsideBitcoins, and EconomyWatch, solidifying his reputation in the financial community.